Category: BLOG

  • Privacy.com Alternatives for People Outside the US

    Privacy.com Alternatives for People Outside the US

    Example scenario: you read a privacy guide that recommends giving every online store its own virtual card, locked to that merchant, so a breach at one shop exposes nothing else. The guide links to Privacy.com. You live in Germany, Kenya or India, and the sign-up page asks for a US bank account and a Social Security number. The idea is sound. The tool is not available to you.

    This article looks for a fair Privacy.com alternative for people who do not live in the US. No single service copies Privacy.com feature for feature outside the US, so the useful question is which of its benefits you need most, and which alternative delivers them where you live.

    Why Privacy.com is US-only

    Privacy.com issues cards linked to a US bank account and must verify its users under US rules. Privacy.com’s eligibility page says it is available to US citizens or legal residents aged 18 or over who have a checking account at a US bank or credit union, a US phone number that can receive texts and, for most users, a Social Security number. International addresses are not supported, so even US citizens abroad need a US residential address.

    What you are trying to replace

    Privacy.com is popular for a handful of features. Decide which ones matter to you before you compare alternatives:

    • Separate cards per merchant, so a breach at one store does not expose your main card.
    • Merchant-locked cards that only work at the first merchant that charges them.
    • Single-use cards that close after one payment.
    • Spending limits per card, per month or per transaction.
    • Pausing and closing cards instantly to stop unwanted charges.

    Merchant locks and per-card limits are the hardest to find outside the US. Separate cards and the ability to freeze them are much easier.

    The alternatives

    Revolut

    Revolut lets customers create virtual cards in its app, including disposable cards whose details change after each payment.

    Good for: people in countries Revolut serves who want several virtual cards and one-off disposable numbers in one app.

    Limits: you must live in a supported country and pass identity checks. It is a full account rather than a privacy tool, so cards are tied to your name and account.

    Wise

    Wise offers virtual debit cards linked to its multi-currency account, which can hold 40+ currencies.

    Good for: people who already use Wise and want a separate card number for online shopping in several currencies.

    Limits: the card is only issued in certain countries, listed in Wise’s help center, and identity verification is required. Wise is built for money movement, not merchant-level privacy controls.

    Getsby

    Getsby is a European payment-masking service that issues virtual Mastercard cards. Its own pages say it is open to residents of the EEA, EFTA and the UK aged 18 or over.

    Good for: Europeans who want cards designed for privacy rather than banking.

    Limits: residents outside those regions cannot sign up. Check its current fees and card types on its site before use.

    Your own bank’s virtual cards

    Many banks now offer virtual card numbers in their apps, and some let you delete and recreate them.

    Good for: a quick, free way to keep your physical card number off shopping sites.

    Limits: features vary widely, the card still draws on your main account, and many banks offer only one virtual number.

    Crypto-funded prepaid card providers

    Providers such as PST.NET, Ezzocard and Vizovcc sell virtual cards funded with crypto rather than a bank account.

    Good for: people without a supported bank, or who want spending kept entirely separate from their bank account.

    Limits: fee models differ (top-up percentages, per-card prices, subscriptions), some cards cannot be reloaded, and any merchant can decline a prepaid card. Read recent reviews and the provider’s terms.

    Comparison table

    OptionWho can sign upFundingPrivacy.com features it coversMain limit
    Privacy.comUS citizens or legal residents with a US bankUS bank accountAll of the aboveUS only
    RevolutResidents of supported countriesBank transfer, cardSeparate and disposable cards, freezingCountry coverage; full account
    WiseCard issued in listed countriesBank transfer, card, incoming paymentsSeparate virtual cards, freezingCountry coverage; few privacy controls
    GetsbyEEA, EFTA and UK residents, 18+See providerPrivacy-focused virtual cardsEurope only
    Bank virtual cardsCustomers of that bankYour bank accountHides your physical card numberTied to your main account
    Crypto-funded prepaidVaries by providerCryptoSeparate cards with fixed balancesPrepaid acceptance varies; fees differ

    How to choose

    1. Start with where you live. If you are in Europe, Getsby, Revolut and Wise are all worth checking. Elsewhere, check Revolut and Wise country lists, then consider prepaid providers.
    2. Pick the feature you need most. For one-off purchases, disposable cards matter. For subscriptions, a stable card with a capped balance matters more.
    3. Decide how you will fund it. Bank-linked options need a supported bank. Crypto-funded providers do not.
    4. Check merchant acceptance. Some merchants decline prepaid or disposable cards. Look at the merchant’s billing help page.
    5. Be realistic about privacy. These tools hide your main card number. They do not make you anonymous: providers verify customers in line with their rules, and merchants still see the billing details you enter.

    Where Vizovcc fits, and where it doesn’t

    Vizovcc sells prepaid virtual cards from an account balance funded with crypto such as Bitcoin, USDT, USDC or ETH. Signing up needs an email address, and no bank account is needed to fund it. It is not a feature-for-feature Privacy.com replacement, so it is worth being clear about both sides.

    What it offers:

    • A separate prepaid card per merchant, subscription or project, with several cards held in one account.
    • A fixed loaded balance on each card that cannot be overspent, which caps what any merchant can take.
    • Freeze and unfreeze from the dashboard.
    • 3D Secure support, and card pages that show Apple Pay and Google Pay compatibility.
    • About 54 cards across several networks, in USD and many local currencies.

    What it does not offer: merchant-locked cards, single-use numbers or spending limits you set per card. The balance is the limit.

    Other limits: funding is crypto only, each merchant decides whether to accept a prepaid card, and card purchases are final, so choose the card carefully. The company describes the cards on its virtual Visa and Mastercard page. As with any vendor, check the facts against each provider’s current pages.

    FAQ

    Is there a Privacy.com equivalent in Europe?

    Getsby is the closest privacy-focused option for EEA, EFTA and UK residents. Revolut’s disposable cards cover one-off purchases for people in its supported countries.

    Can I use Privacy.com with a VPN or a friend’s US details?

    No. That would break its terms and US verification rules, and the account could be closed with your money in it. Use a service that serves your country.

    Do prepaid virtual cards protect my privacy?

    They keep your bank card number away from merchants and cap what a breach can expose. They are not anonymous payment tools.

    Key takeaways

    • Privacy.com requires US residency, a US bank account and, for most users, an SSN.
    • Merchant locks and per-card limits are rare outside the US. Separate cards and freezing are widely available.
    • Europeans have the most options (Getsby, Revolut, Wise). Elsewhere, crypto-funded prepaid cards fill the gap.
    • Vizovcc offers separate prepaid cards with fixed balances and freezing, not merchant locks or single-use numbers.
    • None of these tools make you anonymous. They limit exposure.

    Choose the one Privacy.com feature you miss most, then pick the option that delivers it in your country. If separate crypto-funded prepaid cards cover what you need, compare the cards at Vizovcc and start with the merchant you trust least.

  • Reloadable vs Single-Use Virtual Cards: Which to Use When

    Reloadable vs Single-Use Virtual Cards: Which to Use When

    Here is a common mix-up (an example, not a real case). A freelancer reads that single-use virtual cards are the safest way to pay online, so she creates one for her design software. The first month goes through. The second month, the renewal is declined, the account drops to the free tier, and a client deliverable sits locked behind an expired plan. The card did what it was built to do: it worked once and then shut down. It was simply the wrong type for a subscription.

    Virtual cards come in more than one type, and the labels get used loosely. A reloadable virtual card, a multi-use card and a single-use card each solve a different problem. This guide explains what each type does, shows which payments suit which type, and gives you a decision matrix you can use the next time you set up a payment.

    The three questions that define a card type

    Most confusion clears up once you separate three questions that providers often blend together:

    1. How many charges can the card accept? A single-use card accepts one payment. A multi-use card accepts many, until it expires or runs out of funds.
    2. Can you add money after you get it? A reloadable card lets you add funds after the first load. A non-reloadable card spends only what it started with.
    3. Where do the funds sit? Some cards hold their own balance. Others draw from a shared account or a line of credit.

    A card can combine these in different ways. A multi-use card can be non-reloadable, and a reloadable card is almost always multi-use. Reading a provider’s terms with these three questions in mind tells you more than the product name does.

    Single-use virtual cards

    A single-use card is a card number generated for one transaction. Once that payment goes through, the number stops working, so a merchant that stores it cannot charge it again.

    Where single-use cards work well

    • One-off purchases from a website you have not used before.
    • Paying a new vendor for the first time without giving them an ongoing payment method.
    • Booking a one-time service where the exact amount is known up front.

    Where they cause problems

    • Subscriptions. The renewal is a second charge, and it will fail.
    • Ad accounts. Platforms charge repeatedly as spend builds up.
    • Refunds. Returning money to a closed number can take extra steps, depending on the provider.
    • Pre-authorizations. Hotels and rentals often place a hold and charge later, which can fail on a number that has already been used.

    Multi-use virtual cards

    A multi-use card keeps working across many payments until it expires, is closed or runs out of money. This is the type most businesses use for recurring vendors: one card per subscription, tool or ad account. The card number stays the same, so renewals keep going through, and if one vendor is breached you replace only that card.

    A multi-use card does not have to be reloadable. Some are funded once with a fixed amount and keep accepting charges until that amount is spent.

    Reloadable virtual cards

    A reloadable card lets you add money after you first get it. In the US, the CFPB describes these as cards you can add more money to, sometimes called general purpose reloadable (GPR) cards, and the CFPB’s prepaid card glossary notes that some cards must be registered before they can be reloaded.

    Reloading is useful when you want to keep the same card number on a vendor for a long time while controlling how much it holds. You top up the card for each month’s expected charges, and anything beyond that is declined. The trade-off is effort: someone has to remember to reload it, and a missed reload looks exactly like any other decline to the vendor.

    Comparison table

    FeatureSingle-useMulti-use, fixed fundsReloadable
    Number of chargesOneMany, until funds or validity run outMany
    Add money laterNoNoYes
    Works for subscriptionsNo, renewals failYes, while funds lastYes
    Works for ad accountsNoYes, while funds lastYes
    Exposure if a merchant leaks itVery low, the number is spentLimited to the funds on that cardLimited to the funds on that card
    Ongoing effortNew card for each purchaseReplace when funds run lowReload on schedule

    Decision matrix by payment type

    PaymentBest typeWhy
    One-off purchase on an unfamiliar siteSingle-useThe number cannot be reused if the site stores it
    Monthly or annual SaaS subscriptionMulti-use or reloadableRenewals need the same number to keep working
    Ad account billingMulti-use or reloadable, one per accountPlatforms charge often and pause ads on a decline
    Usage-based cloud or API billingReloadable or multi-use with a bufferCharges vary month to month
    First payment to a new vendorSingle-useLets you test the vendor before giving it a lasting card
    Hotel or rental with a deposit holdPhysical or multi-use cardHolds and later charges can fail on a spent number

    A simple rule covers most cases: if the merchant will ever charge you again, do not use a single-use card.

    Where ZenVCC fits

    It helps to be precise about which type a provider offers, because product names can mislead. ZenVCC is a prepaid virtual card platform, not a bank. It does not offer single-use or disposable numbers. Its cards are multi-use prepaid cards: you fund one account balance with crypto (Bitcoin, USDT on TRC-20 or Solana, TRX or SOL), buy a card from that balance, and the card keeps accepting charges while it has funds and stays valid for three years from the day it is ready.

    On reloading, read the fine print. Some cards in the ZenVCC catalog carry “Reloadable” in their names, such as the Mastercard Reloadable Classic, but ZenVCC’s own card-declines page says cards can’t be topped up from the dashboard, and advises using a card that covers the charge when one runs low. In practice, treat these as multi-use cards with fixed funds and plan to buy a new card rather than reload an old one.

    That makes it a fit for the middle column of the table: one card per subscription, tool or ad account, with costs that are easy to plan. Each card has a one-time $10 issue fee, each payment costs $0.10, and there is no monthly fee. If a card cannot be prepared, the full amount, including the issue fee, returns to your balance. For one-off purchases on unfamiliar sites, a provider that issues true single-use numbers is the better choice. You can read ZenVCC’s guide to how its virtual cards work for the details on funding and fees.

    Mistakes to avoid

    • Putting a subscription on a single-use card. The renewal will fail, sometimes without a clear warning from the vendor.
    • Assuming “reloadable” in a name means you can reload it. Check the provider’s terms for how, and whether, funds can be added.
    • Letting a fixed-funds card run dry. Track renewal dates and replace the card before the balance gets close to the next charge.
    • Sharing one multi-use card across many vendors. You lose most of the protection that separate cards give you.

    Key takeaways

    • Card type comes down to three questions: how many charges, whether funds can be added, and where the funds sit.
    • Single-use cards suit one-off purchases and first payments to new vendors, never subscriptions.
    • Multi-use and reloadable cards suit anything that bills more than once, ideally one card per vendor.
    • Product names are not proof. Confirm in the terms whether a card can be reloaded.

    Look at your last month of card charges and sort each one into the matrix above; you will quickly see which payments need which card type. If you want multi-use prepaid cards for recurring vendors, take a look at ZenVCC and compare it with your current setup.

  • Virtual Cards and KYC: What Is Normally Required and Why No-KYC Claims Deserve Skepticism

    Virtual Cards and KYC: What Is Normally Required and Why No-KYC Claims Deserve Skepticism

    Search for a crypto-funded virtual card and half the results promise “no KYC.” Then you read reviews from people whose balances were frozen when the provider suddenly asked for a passport. Which is it, and what should you actually expect to hand over?

    Quick answer

    1. Card programs sit inside regulated payment systems, so identity checks (KYC) and anti-money-laundering controls (AML) are normal.

    2. Low-value, limited products may need fewer checks in some jurisdictions. Higher limits and unusual activity bring more.

    3. “No KYC” usually means “not yet.” Checks can arrive later, often at the worst moment, such as a withdrawal.

    4. A trustworthy provider publishes its AML policy and tells you what it may ask for, and when.

    What KYC and AML mean for a card

    KYC (know your customer) is the process of identifying who holds an account and verifying that the identity is real. AML (anti-money laundering) is the wider set of controls that sits around it: screening customers against sanctions and politically exposed person lists, monitoring transactions, and reporting suspicious activity to the authorities.

    For a card, the obligations usually fall on the issuer, the regulated bank or e-money institution, and on any program manager that runs the card on the issuer’s behalf. Visa and Mastercard require their issuers to follow applicable AML law. A crypto-funded card adds another layer. Wherever the crypto is received and converted, virtual asset rules can apply as well, including the FATF “travel rule” that asks crypto service providers to pass sender and recipient information along with transfers.

    So even when the website you use is a small brand, there is usually a regulated party somewhere in the chain with legal duties to know who its cardholders are.

    Why prepaid cards are treated on a sliding scale

    AML rules in most major jurisdictions are risk-based. The more value and flexibility a product offers, the more checks it requires. That is why a single-use gift card at a supermarket and a reloadable card with a high monthly limit are handled differently.

    Typical patterns across regulated programs look like this. The specifics vary by country, issuer and program, so read this as the general shape, not as any provider’s rules:

    Product profileWhat is typically checkedWhy
    Low-value, non-reloadable gift or prepaid cardLittle or no identification, within strict value limitsLow risk; the limits do the work
    Reloadable prepaid card, moderate limitsName, date of birth, address, sanctions screening; often ID verificationRepeated loading raises the risk
    Higher limits or business useID and proof of address; business registration and owners for companiesLarger amounts need a verified identity
    Unusual activity at any levelSource-of-funds questions, more documents, possible account freezeOngoing monitoring is a legal duty

    In the EU, for example, simplified due diligence for prepaid products is allowed only below set value limits, and remote online payments above a small amount need identification [VERIFY: current EU thresholds under the AML directives, and the changes when the EU AML Regulation applies from July 2027]. In the US, FinCEN’s prepaid access rule places customer identification duties on providers of prepaid access above certain limits [VERIFY: current FinCEN prepaid access thresholds]. The point is not the exact numbers. It is that “how much” and “how often” decide what gets checked.

    Why “no-KYC” claims deserve skepticism

    When a card is marketed as needing no identification, one of three things is usually true.

    1. The checks are postponed, not removed. The product lets you sign up and deposit without ID, then asks for documents when you hit a limit, try to withdraw, or trigger a monitoring rule. Your money is already inside by then, and you can’t leave without complying. This matches a pattern in user reviews of crypto card providers on Trustpilot: deposits “rejected without explanation” and withdrawals stuck for weeks.

    2. The limits are low and stated in small print. A product can lawfully skip some checks if its value limits are tight enough. That is legitimate, but it is not what “no KYC” headlines imply. Read the limits, not the slogan.

    3. The program isn’t compliant. If nobody in the chain is doing the checks the law requires, the issuer or the network can shut the program down, and balances can be frozen while that happens. Cases like the Wirecard collapse in 2020 show how quickly cards stop working when the regulated layer underneath them has a problem, even for programs that did nothing wrong.

    There is a practical cost too. Card programs that attract fraud get their BIN ranges flagged by merchants, which leads to more declines for every cardholder on that range. A product that markets itself on avoiding checks tends to attract exactly the activity that gets its cards blocked.

    None of this means you should hand your documents to anyone who asks. It means the real question is not “KYC or no KYC” but “what checks, when, and how is my data handled?”

    No credit check is not the same as no identity check

    These two phrases get blurred together, and they mean different things.

    A credit check asks whether you are likely to repay borrowed money. A prepaid card lends you nothing. You spend your own balance, so there is nothing to assess, and “no credit check” is simply accurate for prepaid products.

    An identity check asks who you are. It applies whether or not credit is involved. A card can honestly say “no credit check” and still be required to verify identity, now or at higher limits.

    What a transparent provider should tell you

    Before you deposit, you should be able to answer these from the provider’s own pages or a written support reply:

    ☐  Is there a published AML policy, written for this provider?

    ☐  What information may be requested, and at which limits or activities?

    ☐  What happens to a balance while a check is pending?

    ☐  Can you withdraw unspent funds if you choose not to complete a check?

    ☐  Who is the card issuer, and in which jurisdiction?

    ☐  How long are identity documents kept, and who can see them?

    ☐  How do you appeal a frozen account or a rejected deposit?

    A provider that can’t answer these clearly is asking you to take the risk on trust.

    As one example, VCCBuy’s AML policy is published on its site. VCCBuy issues prepaid virtual cards funded with crypto. It states plainly that it is not a bank, and it advertises no credit check, which, as above, is a different thing from identity checks. Read the policy before you deposit, and ask support in writing what applies at the volume you expect. The same goes for any provider, and for alternatives such as bank-issued virtual cards, which normally complete KYC when you open the account.

    Preparing for KYC the right way

    Checks are smoother when you expect them. A short procedure:

    1.  Use your real, current details at signup, the same name and address that appear on your ID.

    2.  Keep your billing address consistent. Save the same address on the card that you used for verification.

    3.  Keep records of where your crypto came from. Exchange statements, invoices for freelance income and wallet transaction histories answer most source-of-funds questions quickly.

    4.  Size your activity honestly. If you expect high volume, tell the provider and complete the higher-level checks up front, rather than meeting them mid-withdrawal.

    5.  Don’t split deposits to stay under a limit, and never use someone else’s identity or account. Structuring transactions to avoid reporting is itself an offense in many jurisdictions, and it will get an account closed.

    6.  Protect your data. Upload documents only through the provider’s official dashboard, never through a chat link someone sends you.

    Wanting privacy is reasonable. The legitimate route to it is asking how your data is stored and kept, choosing providers with clear retention policies, and sharing only through official channels. Avoiding identity checks altogether is not.

    FAQ

    Is it legal to use a virtual card without KYC? Some low-value prepaid products can legally operate with limited checks, within strict limits set by local law. Whether a specific product is compliant depends on the issuer and the jurisdiction. If a product’s main selling point is avoiding checks, treat that as a warning sign.

    Why did my provider ask for documents after months of normal use? AML monitoring is ongoing. A larger deposit, a new pattern of spending, a rule change or a request from the issuer can all trigger a review. Answering promptly, with records ready, is usually the quickest way through.

    Is it safe to upload my ID to a crypto card provider? It is as safe as the provider’s data handling. Check its privacy policy, ask how long documents are kept, and upload only through the official site. Never send ID images through Telegram or WhatsApp.

    Conclusion

    KYC is part of how card programs stay connected to Visa and Mastercard, and the products that promise to skip it often bring it back later at a worse time. Look for providers that publish their AML policy and explain what they may ask for and when. If you’re comparing options, read VCCBuy’s policy alongside the others, and choose the provider whose rules you understand before you deposit.

    About the author: [Author name] is a payments and fintech writer at VCCBuy (https://vccbuy.net/), where they cover virtual cards, card networks and spending stablecoins online. They write about how compliance rules shape card programs and what cardholders should expect from providers.

    Disclosure: the author writes for VCCBuy, which is mentioned in this article.

  • When a Crypto Card Program Shuts Down: What Happens to Your Balance and How to Protect It

    When a Crypto Card Program Shuts Down: What Happens to Your Balance and How to Protect It

    The email arrives on a Tuesday: “We are winding down the card program. Please withdraw your remaining balance.” You have a few hundred dollars on the card, three subscriptions billing to it, and a deadline you didn’t know existed until now.

    Quick answer

    1. Card programs end for reasons outside your control: an issuer fails, a partner is acquired, or the business decides the program no longer pays.

    2. Shutdowns usually follow the same stages: funding stops, then spending stops, then a withdrawal window closes.

    3. Your protection is simple. Keep the balance close to what you will spend in the next few weeks, and withdraw the rest.

    How a crypto card program is built

    The card in your dashboard is the visible tip of several companies working together. Knowing the layers tells you where a shutdown can start.

    • The brand or front end: the app or website you deposit crypto into. It may be an exchange, a DeFi protocol or a card service.
    • The program manager or infrastructure provider: runs card issuing, processing and compliance for the brand.
    • The issuer: the regulated bank or e-money institution whose license the card is issued under.
    • The card network: Visa or Mastercard, which routes authorizations and sets the rules.

    Any one of these can end the program. The brand can lose interest, the program manager can be sold, and the issuer can fail or exit the market. You usually have a relationship only with the brand, so you hear about a problem last.

    Four cases, four different causes

    CaseYearWhich layer failedWhat users experienced
    Wirecard2020Issuer and processorCard spending and top-ups stopped for UK and European users of affected crypto cards
    Infini2025Brand (business decision)Card services stopped; withdrawals stayed open
    Moonwell Card2026Infrastructure provider acquiredFunding disabled, then purchases, then a withdrawal deadline of 6 Sep 2026
    1inch Card2026Brand winding downNew sign-ups stopped; users told to withdraw or spend by 18 Dec 2026

    Wirecard, June 2020. When Wirecard filed for insolvency, crypto debit cards that relied on it stopped working for UK and European customers. Decrypt reported that Crypto.com and TenX users could no longer spend or top up. Both companies said customer funds were safe. Crypto.com said it would credit users’ crypto wallets with amounts equal to their card balances. The money wasn’t lost, but the cards were useless overnight, with no warning to the people holding them.

    Infini, June 2025. The stablecoin card service announced in June 2025 that it was stopping card services. Reports cited compliance costs and profitability [VERIFY: Infini’s stated reason and the exact announcement date]. Withdrawals and its yield product kept running. Earlier that year, Infini had also suffered a separate smart-contract exploit of about $49 million. Coverage generally treats the card closure as a business decision rather than a result of the exploit.

    Moonwell Card, 2026. Crypto Briefing reported that the card ran on infrastructure from Cypher, which was acquired by the payments company Nium in July 2026. Under the new owner the program didn’t continue. New funding was disabled, purchases stopped after 7 August 2026, and users were told to withdraw before 6 September 2026 or risk losing access.

    1inch Card, 2026. In October 2026, 1inch stopped new card registrations and advised users to withdraw or spend their balances by 18 December 2026. It said it could not guarantee the cards would stay operational until then. According to Crypto Briefing, the issuer’s published terms let users redeem remaining balances for up to six years after account closure. No reason for the wind-down was given.

    What actually happens to your balance

    The outcome depends on where your money sits when the program ends.

    Money in an e-money or bank balance with the issuer. In many jurisdictions, e-money issuers must keep customer funds separate from their own and let customers redeem them [VERIFY: safeguarding and redemption rules in the issuer’s jurisdiction]. That is why the 1inch terms describe a redemption period. Your money is usually recoverable, but slowly, through a process you didn’t choose.

    Crypto held by the front end before conversion. This sits outside card-network rules. What happens to it depends on the provider’s terms and its solvency.

    Pending transactions and refunds. A merchant refund that arrives after the card is closed has to find its way back to you through the issuer. That can take time and paperwork.

    The pattern across the cases is consistent, and it gives you a timeline to plan around:

    StageWhat still worksWhat you should do
    AnnouncementUsually everythingMove recurring charges to another card; plan the withdrawal
    Funding disabledSpending and withdrawalsStop topping up; spend or withdraw the balance
    Spending disabledWithdrawals onlyWithdraw immediately
    Withdrawal deadline passesPossibly a slow redemption process, or nothingContact support and the issuer in writing; keep records

    Wirecard shows the worst case. Every stage happened at once, without notice. If you can’t count on a warning, the only protection is what you choose to keep on the card in the first place.

    Keep balances lean: the rule that works for any provider

    A crypto card is a spending tool, not a savings account. Treat its balance like cash in your wallet: enough for what is coming up, and no more.

    A practical sizing rule:

    • Balance = known charges for the next 2–4 weeks + a small buffer. Count subscriptions, ad thresholds and planned purchases.
    • Hold the rest in your own wallet, where you control the keys and a card program decision can’t touch it.
    • Top up on a schedule. Weekly or before each known charge, so you never feel tempted to preload months of spending.

    The cost of this discipline is a few extra top-ups and the network fees that come with them. The benefit is that if any program in the chain fails, your exposure is a few weeks of spending, not your savings.

    A shutdown response procedure

    If you receive a wind-down notice, or a card stops working without explanation:

    1.  Read the notice for dates. Write down the funding cutoff, the spending cutoff and the withdrawal deadline.

    2.  Move recurring charges first. Update subscriptions and ad accounts to another payment method before the spending cutoff, so they don’t fail mid-cycle.

    3.  Withdraw the balance to a wallet you control, on a network you have checked. Don’t wait for the deadline.

    4.  Screenshot everything: the balance, the withdrawal request, the transaction hash and any support replies.

    5.  If the withdrawal fails, contact support in writing, then look up the issuer named in the card terms and ask about its redemption process.

    6.  Watch for scams. Shutdowns attract fake “recovery” agents on Telegram and X. Use only channels listed on the provider’s official site, and never share a seed phrase.

    The same advice applies here

    This applies to every provider, including the company I write for. VCCBuy issues prepaid virtual Visa and Mastercard cards funded with stablecoins and other crypto. It is not a bank. The relevant feature for this article is that unspent balance can be withdrawn to a crypto wallet from the dashboard, and cards can be frozen when you aren’t using them. That makes the lean-balance habit easy to keep: load what you need, spend it, and withdraw anything left. Use VCCBuy that way, rather than as a place to store funds.

    The same habit works with bank-issued virtual cards, prepaid gift cards and any other spending tool funded ahead of time.

    Lean-balance checklist

    ☐  Card balance covers only the next 2–4 weeks of known charges

    ☐  The rest is held in a wallet you control

    ☐  Recurring charges are listed, so you can move them quickly

    ☐  A second payment method is ready for critical subscriptions

    ☐  You know the withdrawal route and have tested it once with a small amount

    ☐  You know where to find the issuer’s name in your card terms

    ☐  Provider emails go to an inbox you check

    ☐  Official support channels are bookmarked from the provider’s own site

    FAQ

    If my crypto card program shuts down, is my money gone? Usually not, but it can be slow to recover. In the Wirecard, Infini, Moonwell and 1inch cases, users were told to withdraw, or were credited, or had a redemption route. The risk is delay and paperwork, plus loss if you miss a deadline or the provider itself is insolvent.

    Should I keep a large balance to avoid top-up fees? No. Top-up fees are a percentage, so a large balance doesn’t save much per dollar. It just puts more money at risk if a program ends. Frequent small top-ups cost a little more in network fees and limit your exposure.

    How do I know who the issuer of my card is? Check the card terms and conditions, the cardholder agreement or the provider’s legal pages. If no issuer is named anywhere, ask support in writing and treat the absence of an answer as a reason to keep your balance small.

    Conclusion

    Card programs end for reasons no cardholder can control, from an issuer’s collapse to a quiet acquisition. You can control how much is on the card when it happens. Keep balances lean and withdraw what you don’t need, whether you use VCCBuy, a bank-issued virtual card or any other crypto card.

    About the author: [Author name] is a payments and fintech writer at VCCBuy (https://vccbuy.net/), where they cover virtual cards, card networks and spending stablecoins online. They track how crypto card programs are structured and what cardholders can do when one closes.

    Disclosure: the author writes for VCCBuy, which is mentioned in this article.

  • SAP Cloud Platform Integration Monitoring and Error Handling

    SAP Cloud Platform Integration Monitoring and Error Handling

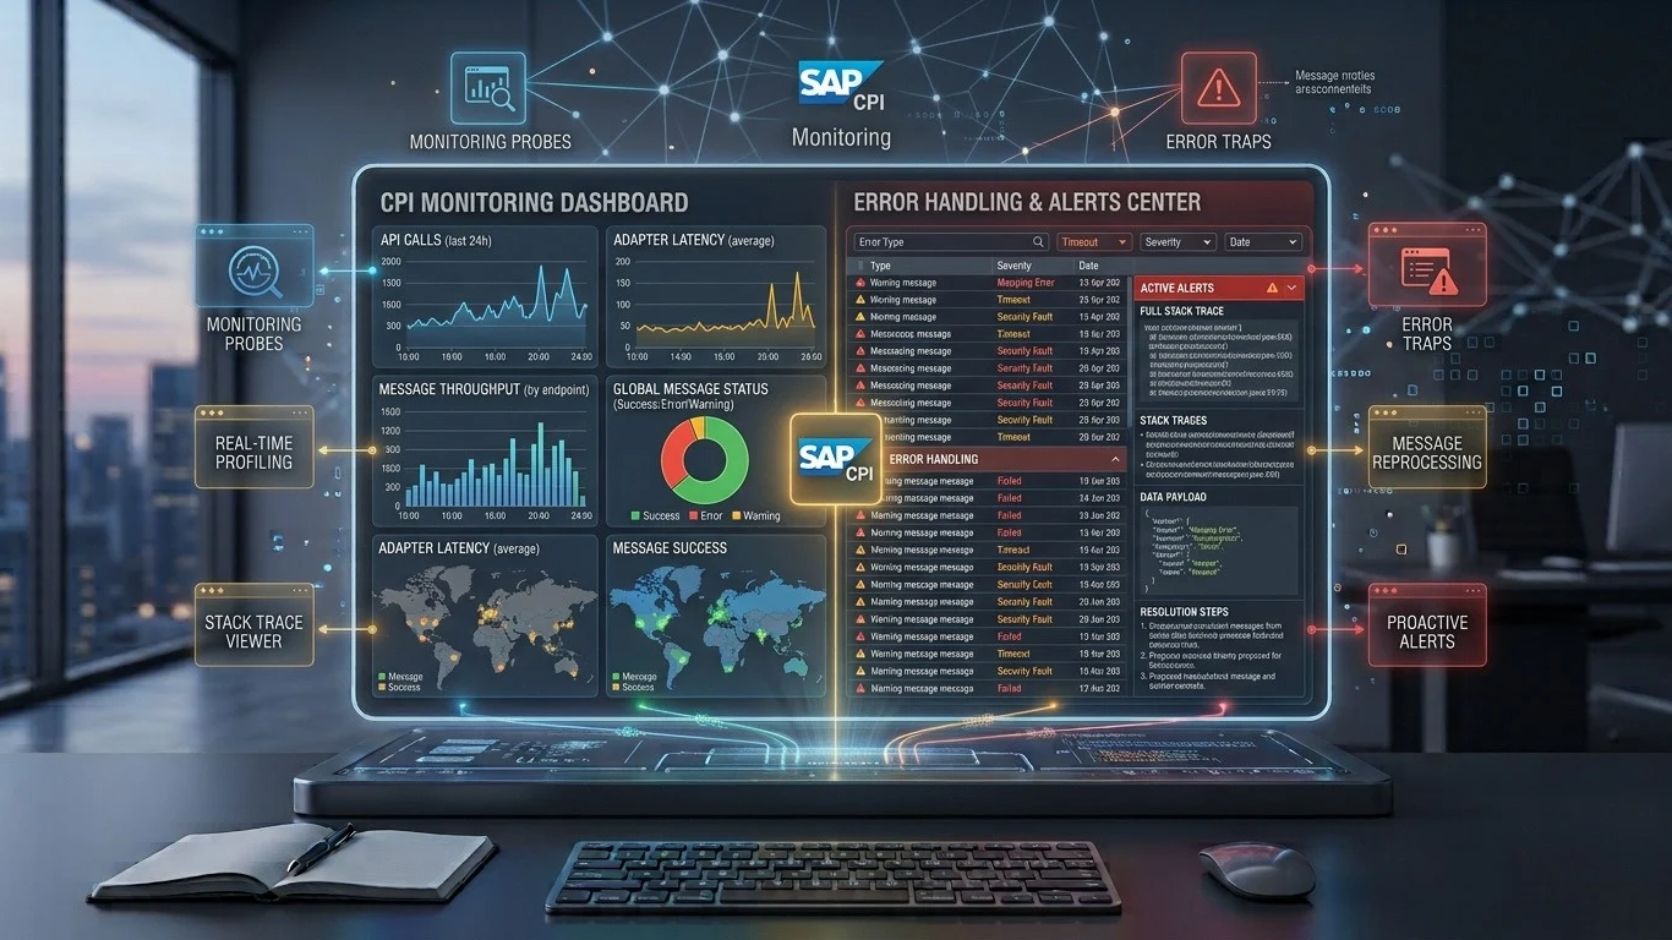
    SAP Cloud Platform Integration, now part of SAP Integration Suite, provides cloud-based capabilities for connecting SAP and non-SAP applications. As integration landscapes grow, monitoring and error handling become essential for maintaining reliable message processing.

    SAP Cloud Integration allows integration teams to monitor message exchanges, identify failed processing steps, analyze errors, and take corrective action. It supports integration scenarios involving SAP S/4HANA, SAP SuccessFactors, SAP Ariba, Salesforce, databases, APIs, file servers, and other enterprise applications.

    A reliable monitoring strategy also depends on proper configuration of integration flows, security, adapters, message processing, and connection settings. Destinations can be used in relevant SAP environments to manage connection information for applications and services.

    What Is SAP Cloud Platform Integration Monitoring?

    SAP Cloud Platform Integration monitoring is the process of observing integration flows, messages, processing status, errors, and runtime behavior.

    An integration flow can process thousands of messages depending on the workload and business scenario. Each message can pass through multiple processing steps before reaching the receiver.

    Monitoring helps determine whether a message was successfully processed or failed during execution.

    For example, an integration flow connecting S/4HANA with Salesforce may perform these steps:

    S/4HANA → Cloud Integration → Message Transformation → Salesforce

    If Salesforce rejects the message because of an invalid field, monitoring can help identify the failed message and provide information about the processing error.

    Why Monitoring Is Important in Cloud Integration

    Enterprise integrations often support business processes that require accurate and timely data exchange. A failure in an integration flow can affect orders, invoices, customer records, inventory data, employee information, or financial transactions.

    Monitoring provides visibility into the runtime behavior of integration flows.

    It can help integration teams identify:

    • Failed messages
    • Processing errors
    • Authentication failures
    • Connectivity problems
    • Mapping issues
    • Invalid payloads
    • Receiver-system errors
    • Timeout conditions

    Monitoring is therefore an important part of operating SAP Cloud Integration in production environments.

    SAP Cloud Integration Message Monitoring

    Message monitoring provides information about messages processed by integration flows.

    Depending on the available monitoring functions and configuration, users can inspect message processing status and investigate failed executions.

    A message can have a successful or failed processing state. A failed message indicates that processing did not complete as expected.

    The monitoring information can help identify the integration flow involved, processing time, message status, and available error details.

    For troubleshooting, the first step is usually to identify the failed message and determine where processing stopped.

    Understanding Integration Flow Errors

    Errors can occur at different stages of an integration process.

    An error may occur when the sender system cannot communicate with Cloud Integration. It can also happen during transformation, routing, authentication, or communication with the receiver.

    For example, an HTTP-based integration can fail because the target endpoint returns an HTTP error response.

    Common HTTP status codes include:

    400 Bad Request: The request contains invalid or unacceptable information.

    401 Unauthorized: Authentication credentials are missing or invalid.

    403 Forbidden: The authenticated user or client does not have sufficient permission.

    404 Not Found: The requested resource or endpoint cannot be found.

    500 Internal Server Error: The receiving application encountered an internal error.

    The exact cause must be evaluated using the message processing details and the target application’s response.

    Common Causes of SAP Cloud Integration Errors

    Integration errors generally originate from configuration, connectivity, authentication, data, mapping, or application behavior.

    A connection error may occur when a target system is unavailable or when the endpoint is incorrect. Authentication errors can occur when credentials, certificates, OAuth configuration, or authorization settings are invalid.

    Data errors can happen when a required field is missing or when the payload does not match the expected structure.

    Mapping errors occur when source and target data structures are incompatible or when a transformation expression cannot process the supplied value.

    Application errors occur when the receiving system accepts the connection but rejects the business data.

    Understanding the error category helps reduce troubleshooting time.

    Monitoring Integration Flows

    Integration flow monitoring helps determine whether the designed processing logic is working as expected.

    A typical integration flow may contain a sender adapter, message transformation, content modifier, router, mapping step, and receiver adapter.

    If the message fails, monitoring can help identify which stage produced the error.

    For example:

    Sender → Mapping → Router → Receiver

    If the receiver rejects the message, the mapping and routing stages may have completed successfully. This distinction is useful because it narrows the investigation to the receiver communication or target application.

    Error Handling with Exception Subprocesses

    SAP Cloud Integration supports exception handling through Exception Subprocesses.

    An Exception Subprocess can define actions that should occur when an error is raised inside an integration process.

    Depending on the design, error handling can include logging information, setting message properties, creating an error response, or routing the message to an appropriate processing path.

    A well-designed exception process should provide enough information to identify the problem without exposing sensitive credentials or confidential business data.

    Exception handling is especially important for integrations that process financial transactions, customer information, orders, invoices, or other critical business messages.

    Retry and Reprocessing Considerations

    Not every integration error requires the same recovery method.

    A temporary connectivity failure may be suitable for retry logic. A permanent data validation error normally requires correction of the message or source data before processing again.

    For example, if a receiver system is temporarily unavailable, retrying the request may succeed after the service becomes available.

    If a customer record contains an invalid mandatory field, repeated retries will not resolve the underlying problem.

    The error-handling strategy should therefore distinguish between temporary technical failures and permanent business or data errors.

    Destinations and Error Troubleshooting

    Destinations can contain connection information used by applications and services to communicate with target systems.

    When an integration depends on a destination configuration, an incorrect endpoint or authentication setting can cause connection failures.

    For example, a destination may contain information such as a target URL, authentication type, and connection properties.

    When troubleshooting a destination-related problem, the configuration should be checked against the expected endpoint and authentication requirements.

    Incorrect URLs, expired certificates, invalid credentials, missing permissions, and incorrect authentication types can all affect connectivity.

    Using centrally managed Destinations where supported can also help separate connection configuration from application or integration logic.

    Authentication Errors

    Authentication errors are common in enterprise integration environments.

    Cloud Integration may need to authenticate against S/4HANA, APIs, third-party applications, or other services.

    Authentication can use different mechanisms depending on the connected system. These may include OAuth 2.0, basic authentication, client certificates, or other supported methods.

    A 401 response generally indicates an authentication problem, while a 403 response generally indicates that the authenticated identity does not have the required permission.

    The troubleshooting process should verify the authentication method, credentials or certificate status, token configuration, and authorization settings.

    Authorization and Permission Problems

    Successful authentication does not automatically provide access to every resource.

    An application may authenticate successfully but still receive a permission error when accessing a specific API or business object.

    For example, an S/4HANA API may require specific authorizations. A third-party application may also restrict access to particular resources.

    Authorization problems should therefore be checked separately from authentication problems.

    The required permissions depend on the application, API, user, service account, and security architecture.

    Mapping Errors and Data Validation

    Mapping is a common processing stage in Cloud Integration.

    A source system and target system may use different field names, data types, formats, and structures.

    For example:

    Source: CustomerID

    Target: CustomerNumber

    The integration flow must map the source value to the appropriate target field.

    Errors can occur when a required source value is missing, when a target field expects a different data type, or when a transformation function receives an invalid value.

    Testing should include valid and invalid payloads to identify mapping problems before production deployment.

    Connectivity and Network Errors

    Connectivity errors can occur when the target application is unavailable or inaccessible.

    Potential causes include incorrect endpoint URLs, DNS problems, firewall restrictions, certificate issues, network configuration, or service outages.

    In hybrid environments, additional connectivity components may be required to connect cloud-based integration services with on-premise applications.

    For example:

    On-Premise SAP System → Secure Connectivity → Cloud Integration → External Cloud Application

    If the connection fails, each component in the communication path needs to be considered.

    Monitoring APIs and External Systems

    Cloud Integration can connect to systems through APIs and web services.

    When an API call fails, troubleshooting should consider both the integration flow and the target API.

    Important information can include the request method, endpoint, HTTP status code, response message, authentication method, and payload structure.

    Common HTTP methods include GET, POST, PUT, PATCH, and DELETE. The supported methods depend on the API.

    An API may return a technically successful HTTP response while the business operation still produces an application-level error. Monitoring therefore needs to consider both transport-level and business-level responses.

    Logging and Sensitive Data

    Logs are useful for troubleshooting, but integration logs may contain business information.

    Customer information, employee data, financial information, credentials, tokens, and other sensitive information should not be exposed unnecessarily in logs.

    Logging should be designed according to the organization’s security and data protection requirements.

    Integration developers should avoid storing passwords, access tokens, or other secrets in message content or custom logging output.

    The level of diagnostic information should provide enough detail for troubleshooting while limiting unnecessary exposure of sensitive data.

    Monitoring Scheduled and File-Based Integrations

    Not every S/4HANA integration uses APIs.

    Some business processes use file-based integration through protocols such as SFTP.

    A file integration may follow this pattern:

    Source Application → SFTP → Cloud Integration → S/4HANA

    Errors can occur when the file is missing, incorrectly named, unavailable, malformed, or contains invalid records.

    File encoding, delimiters, headers, file structure, and required fields should match the integration flow’s expected format.

    Monitoring can help identify whether the file was received and whether processing completed successfully.

    Error Handling for S/4HANA Integration

    S/4HANA integration can involve APIs, OData services, IDocs, SOAP services, and other interfaces.

    Each interface type can generate different errors.

    For example, an OData service may return an HTTP error, while an IDoc process can involve status information related to document processing.

    Error handling should therefore consider the interface technology and the business process.

    A useful monitoring design connects technical errors with business context. For example, an error involving a sales order should provide enough information to identify the affected integration message without exposing unnecessary customer information.

    Using Destinations in Integration Architecture

    Destinations can be used to manage connection information within supported SAP architectures.

    A destination can identify where a service or application is located and how the connection should be established.

    This approach can be useful when multiple applications need consistent access to the same service.

    Destination configuration should be reviewed when an integration starts failing after an endpoint, authentication method, certificate, or system environment changes.

    For example, moving from a development environment to a production environment may require different endpoint and authentication configurations.

    The destination should point to the correct environment and use the appropriate security configuration.

    Testing Error Handling Before Production

    Error handling should be tested before an integration flow is used in production.

    Testing should include successful processing as well as expected failure conditions.

    A test scenario can intentionally use an invalid authentication credential to verify authentication error handling. Another test can provide an incomplete payload to verify data validation and mapping behavior.

    Connectivity failures can also be simulated where the testing environment permits it.

    The objective is to confirm that the integration flow produces useful diagnostic information and does not expose sensitive data.

    A Practical Monitoring and Troubleshooting Process

    When an integration fails, the investigation should start with the message processing status.

    First, identify the affected integration flow and message. Then review the error information and determine whether the failure occurred during connectivity, authentication, transformation, routing, or receiver processing.

    Next, verify the relevant configuration. This can include adapters, APIs, mappings, certificates, credentials, endpoints, and Destinations.

    After correcting the underlying issue, the message can be reprocessed when the integration scenario and recovery design support reprocessing.

    The final step is to verify that the message reaches the target system successfully and that the business transaction is complete.

    Best Practices for SAP Cloud Integration Monitoring

    Monitoring should be included as part of the integration design rather than added only after deployment.

    Integration flows should have clear names and understandable processing structures. Error handling should distinguish temporary technical failures from permanent business-data problems.

    Security-sensitive information should not be unnecessarily written to logs.

    Monitoring should also consider business impact. A failed message related to an invoice or payment process may require different operational attention from a non-critical informational message.

    Regular review of failed messages can reveal recurring problems such as expired certificates, incorrect mappings, unavailable endpoints, or insufficient authorizations.

    Frequently Asked Questions

    What is SAP Cloud Platform Integration monitoring?

    SAP Cloud Platform Integration monitoring is the process of tracking integration flow execution, message status, errors, processing information, and runtime behavior.

    What are the most common Cloud Integration errors?

    Common errors include authentication failures, authorization problems, invalid payloads, mapping errors, connectivity issues, unavailable endpoints, timeout errors, and receiver application failures.

    How are errors handled in SAP Cloud Integration?

    Errors can be handled using exception subprocesses, validation logic, routing, logging, retry strategies, and appropriate recovery procedures. The exact design depends on the integration scenario.

    What are Destinations in SAP Cloud Integration?

    Destinations provide connection-related information for accessing applications or services in supported SAP environments. They can contain endpoint and authentication configuration.

    Can Destinations cause integration failures?

    Yes. An incorrect endpoint, invalid authentication configuration, expired certificate, or insufficient authorization associated with a destination can contribute to connection or access failures.

    How can I troubleshoot an S/4HANA integration failure?

    Start by identifying the failed message and integration flow. Review the processing error, then check the relevant adapter, API, mapping, authentication, authorization, endpoint, and destination configuration.

    What is an Exception Subprocess?

    An Exception Subprocess is an integration-flow component used to define processing logic for handling errors raised during message processing.

    Should sensitive information be included in integration logs?

    Sensitive information should not be logged unnecessarily. Logging should be designed to provide useful diagnostic information while protecting credentials, tokens, personal information, and confidential business data.

    Can Cloud Integration handle temporary connectivity failures?

    Integration flows can be designed to handle certain temporary failures through retry or error-handling strategies. The appropriate approach depends on the receiver system and the type of error.

    Conclusion

    SAP Cloud Platform Integration monitoring and error handling are essential for reliable enterprise integration. Monitoring provides visibility into message processing, while error-handling mechanisms help identify and manage failures caused by connectivity, authentication, authorization, mapping, data, and application problems.

    A strong

  • How Remittance Platforms Use Virtual Card Issuing for Instant Delivery

    How Remittance Platforms Use Virtual Card Issuing for Instant Delivery

    Remittance platforms increasingly use virtual card issuing to convert approved transfers into immediately usable payment credentials. Instead of waiting for bank settlement or cash pickup, recipients receive tokenized card details through wallets or secure links and can spend funds at once. This model improves liquidity access, compresses payout time, and expands acceptance options, but its effectiveness depends on issuer connectivity, fraud controls, fee design, and delivery mechanics that merit closer examination.

    How Virtual Card Issuing Works in Remittances

    Virtual card issuing in remittances enables a transfer provider to convert approved funds into a digitally generated payment credential that can be delivered to the recipient in near real time.

    After transaction screening, the platform submits issuance instructions through a processor or card network connected to a sponsoring issuer. The system generates a tokenized card number, expiration date, and security code, then binds available balance and usage parameters to that credential.

    Delivery typically occurs through the provider application, SMS link, or digital wallet provisioning flow. Controls may restrict merchant category, geography, transaction count, or validity period, supporting compliance and risk management.

    Among the principal virtual card advantages are reduced cash handling, programmable spending controls, and streamlined reconciliation.

    These mechanics improve remittance efficiency by standardizing disbursement and integrating settlement data with platform reporting workflows.

    Why Instant Remittance Delivery Matters

    Instant remittance delivery strengthens user trust by reducing settlement uncertainty and providing immediate confirmation of fund availability.

    It also improves access to urgent liquidity, enabling recipients to address time-sensitive household, medical, or operational expenses without delay.

    In cross-border corridors, faster disbursement enhances convenience by minimizing transfer friction and aligning remittance services with real-time payment expectations.

    Speed Builds Trust

    Accelerating remittance settlement strengthens user confidence by aligning service performance with the urgency that typically defines cross-border transfers. In digital remittance operations, immediacy functions as a mechanism for trust building, reinforcing financial trustworthiness through visible execution quality and predictable outcomes.

    1. Faster delivery creates a measurable speed advantage in crowded payment markets.
    2. Consistent processing enhances service reliability and strengthens transaction confidence.
    3. Frictionless completion improves user experience, reducing perceived operational risk.
    4. Dependable instant fulfillment supports customer loyalty and sustains competitive edge.

    When platforms issue virtual cards for immediate receipt, recipients observe process certainty rather than delay exposure. That perception materially influences platform reputation, repeat usage, and sender retention.

    Over time, speed becomes more than convenience; it operates as verifiable proof of operational discipline, settlement precision, and scalable payment infrastructure.

    Urgent Funds Access

    Urgent access to remitted funds determines whether a transfer merely arrives or actually resolves the recipient’s immediate financial need. In remittance operations, timing directly affects utility, especially when recipients depend on emergency funds for healthcare, rent, utilities, or food purchases.

    Instant disbursement through virtual card issuing supports rapid transactions that convert approved transfers into usable value without procedural delay. This capability improves user experience by reducing settlement friction and mitigating accessibility issues associated with cash pickup or delayed bank posting.

    It also expands financial flexibility, allowing recipients to allocate funds across essential spending categories as circumstances evolve. From an operational perspective, urgent access increases recipient empowerment because remittances function as immediate relief rather than pending support.

    Consequently, delivery speed becomes a measurable determinant of practical remittance effectiveness and service relevance.

    Cross-Border Convenience

    Because remittance recipients and senders often operate across different banking infrastructures, currencies, and regulatory environments, cross-border convenience depends on how quickly transferred value becomes usable at the destination.

    Virtual card issuing improves settlement agility and reduces dependence on correspondent banking delays, strengthening user experience for dispersed households and mobile workers globally.

    1. It enables immediate digital spend without waiting for local account posting.
    2. It mitigates FX timing risk by accelerating access after conversion.
    3. It supports merchant acceptance across established card network rails.
    4. It advances cross border innovation through programmable controls and compliance orchestration.

    For remittance platforms, instant delivery increases transaction certainty, lowers abandonment, and expands service relevance in underbanked corridors.

    The result is a more interoperable payout mechanism aligned with modern expectations for speed, transparency, and operational resilience across fragmented financial ecosystems.

    How Funds Reach Recipients in Seconds

    Modern remittance platforms route approved transfers through pre-funded settlement accounts, real-time payment rails, and issuer processor integrations that minimize intermediary delays. Once compliance screening and authorization are completed, funds are pushed instantly to eligible endpoints, including wallets, bank accounts, or card-linked credentials, according to Recipient preferences and Payment flexibility requirements.

    Processing speed is reinforced by Mobile integration, automated routing logic, and optimized Currency conversion workflows. Instant notifications and Real time updates support Transaction transparency, while concise status messaging improves User experience.

    Platforms also incorporate User education to clarify settlement timing, fees, and delivery conditions across corridors. Accessibility options, such as multilingual interfaces and simplified confirmation steps, help recipients verify availability without contacting support. This architecture reduces settlement friction and enables near-immediate disbursement under normal network and regulatory conditions.

    Why Remittance Platforms Use Virtual Cards

    Many remittance platforms use virtual cards to convert approved transfers into controlled, immediately usable payment credentials without waiting for physical card production or traditional account onboarding. Their appeal centers on operational control and measurable virtual card benefits across payout ecosystems.

    Key reasons include:

    1. improved remittance efficiency through automated issuing, authorization rules, and streamlined settlement workflows.
    2. stronger user experience via instant provisioning, intuitive wallet compatibility, and reduced recipient friction.
    3. broader financial inclusion and remittance accessibility for users lacking conventional banking relationships, supporting recipient empowerment.
    4. higher transaction transparency, cost savings, and digital innovation through traceable spend data, configurable limits, and scalable program management.

    These attributes also encourage user adoption by aligning compliance, treasury oversight, and disbursement flexibility with modern cross-border service expectations in competitive markets globally.

    When Virtual Cards Beat Bank Transfers

    Virtual cards often outperform bank transfers when transaction speed is the primary requirement, particularly where conventional settlement rails introduce processing delays.

    They also provide broader cross-border utility by enabling immediate digital spend in markets where banking access, correspondent coverage, or local payout infrastructure is limited.

    In such cases, virtual card issuance functions as a faster and more flexible disbursement mechanism within remittance operations.

    Speed Over Settlement Delays

    Accelerating recipient access to funds, virtual card issuing can outperform bank transfers where settlement windows, correspondent banking chains, and cut-off times introduce avoidable delay.

    1. Issuers provision credentials instantly, supporting superior transaction speed in time-sensitive digital transactions.
    2. Card-rail authorization bypasses batch-based settlement friction, strengthening payment efficiency and user experience.
    3. Streamlined payment solutions reflect remittance innovation, where technology advancement improves customer satisfaction.
    4. Faster fund usability can support financial inclusion while intensifying market competition among providers.

    From an operational perspective, virtual cards reduce dependency on legacy clearing schedules and manual exception handling.

    That acceleration benefits recipients needing immediate purchasing power rather than deferred account crediting.

    For remittance platforms, speed becomes a measurable service differentiator, reinforcing conversion, retention, and overall service reliability in increasingly competitive payout environments globally.

    Cross-Border Access Advantages

    Beyond faster fund usability, cross-border reach often determines whether a payout method is practical at all. Virtual card issuing expands cross border access by bypassing destination banking limitations, enabling recipients to transact through global card networks, digital wallets, and merchant acceptance points. This structure strengthens financial inclusion where account ownership remains low and mobile accessibility is high.

    Compared with bank transfers, virtual cards can simplify currency conversion at point of use, improve user experience, and increase transaction transparency through real-time authorization data.

    They also adapt more effectively to market dynamics, particularly in corridors with fragmented banking infrastructure or delayed settlement conventions. For remittance providers, this model supports remittance innovation while preserving regulatory compliance through programmable controls, spend restrictions, identity verification, and auditable transaction monitoring across jurisdictions and payout environments.

    Evaluation Criteria Below Enterprise Scale

    Comparing issuing providers on a feature checklist misses the questions that actually determine fit: settlement currencies, funding options, control granularity, and pricing at your realistic volume. For smaller companies, the evaluation is different again — this comparison of virtual card issuing API providers for SMBs focuses on the criteria that matter below enterprise scale, where minimum commitments and setup fees can quietly kill a business case.

    How Recipients Use Virtual Cards Immediately

    Upon receipt, beneficiaries can provision a remittance-linked virtual card to a mobile wallet or use the card credentials directly for e-commerce, bill payment, and other card-not-present transactions without waiting for physical card production or branch pickup. This capability improves recipient experience through instant gratification, user convenience, and real time access, while supporting financial inclusion and broader tech adoption.

    1. Funds become usable immediately after issuance authorization.
    2. Digital wallets enable secure storage and rapid activation.
    3. Card details support seamless transactions for urgent household obligations.
    4. Remote accessibility reduces dependence on cash-out infrastructure.

    From an operational perspective, immediate usability shortens the interval between disbursement and spend readiness. It also accommodates recipients in underbanked environments, where branch distance, delivery delays, and limited banking hours would otherwise impede timely access to remitted value and liquidity.

    How Virtual Cards Work for Online Payments

    For online payments, a virtual card typically begins with issuer-side card generation, where a unique PAN, CVV, and validity window are provisioned for a specific user or transaction context.

    The payment authorization flow then routes merchant-submitted credentials through the card network and issuer controls to verify funding availability, risk parameters, and approval status in real time.

    Security and expiration features, including tokenization, merchant restrictions, and time-bound validity, are designed to reduce fraud exposure while preserving transaction usability.

    Card Generation Process

    Virtual card issuance begins when a remittance platform, often through a sponsoring bank or card processor, generates a unique primary account number, expiration date, and card verification value within its payment infrastructure.

    The card generation process typically includes:

    1. BIN assignment aligned with compliance regulations and market competition.
    2. Parameter configuration reflecting customer preferences, transaction limits, and card design.
    3. Tokenization and credential provisioning to strengthen fraud prevention and user experience.
    4. API orchestration addressing integration challenges, technology advancements, and platform scalability.

    During creation, issuer controls define currency, merchant category restrictions, geographic use, and funding source linkage.

    Data elements are validated against network formatting standards and internal risk rules before activation readiness.

    This structured approach enables remittance providers to create virtual cards rapidly while maintaining operational consistency, governance, and efficient digital delivery across global payment environments.

    Payment Authorization Flow

    Authorization starts when a cardholder submits the virtual card credentials at an online checkout. The merchant’s payment gateway packages the transaction data for routing through the acquiring bank to the relevant card network. The issuer then evaluates available balance, merchant category, geographic rules, and card customization parameters before returning an approval or decline code. This sequence supports payment security, transaction transparency, and user experience across remittance-funded purchases.

    For remittance platforms, authorization logic must align with regulatory compliance obligations, fraud prevention controls, and settlement timetables. Effective orchestration reduces integration challenges between issuer processors, wallet interfaces, and network endpoints.

    Real-time status messaging also informs customer support workflows and strengthens confidence during market competition. As technology adoption expands, efficient authorization becomes a differentiator for cross-border digital disbursement products globally.

    Security And Expiration

    Strengthening transaction controls, security and expiration features define how virtual cards limit exposure in online payments. Within remittance platforms, issuers apply dynamic credentials, merchant controls, and tightly scoped authorization parameters to reduce fraud risk and misuse.

    Core protections typically include:

    1. Single-use or merchant-locked card numbers that narrow acceptance conditions.
    2. Tokenization and encryption aligned with established security protocols across payment rails.
    3. Spend limits and velocity rules that constrain transaction value, frequency, and geography.
    4. Short card expiration windows that automatically invalidate credentials after intended use.

    These mechanisms support instant delivery while preserving operational integrity.

    If intercepted, a virtual credential has limited utility because validity, authorization scope, and lifecycle are predefined. Consequently, virtual card issuing provides remittance providers with a controlled, auditable instrument for remote commerce and payout disbursement.

    How Virtual Cards Connect to Mobile Wallets

    Because mobile wallets function as tokenized payment containers, a virtual card typically connects through a card network provisioning process that maps the issued credential to a device-specific token within the wallet environment.

    This mobile wallet integration allows the recipient to activate credentials through issuer authentication, wallet verification, and token service provider controls without exposing the primary account number.

    Once provisioned, the tokenized card can be presented for contactless in-store transactions, in-app purchases, or online checkout where wallet acceptance exists.

    The process supports lifecycle management features such as suspension, reissuance, and device binding, which strengthen operational control.

    For remittance platforms, these virtual card benefits include faster usability, reduced delivery friction, and broader merchant acceptance, while maintaining compliance with network rules, issuer risk parameters, and authentication standards across supported consumer devices globally.

    How FX and Funding Work for Card Payouts

    Funding and foreign exchange for card payouts are typically structured as a staged flow in which the remittance platform prefunds or draws against a safeguarded balance, converts the sender currency into the settlement or billing currency, and then instructs the issuer or processor to load the resulting value onto the virtual card.

    1. Funding sources include client balances, bank transfers, and treasury credit lines.
    2. Currency conversion pricing reflects market trends, spread management, and transaction fees.
    3. Risk assessment governs rate locks, fraud screening, liquidity controls, and regulatory compliance.
    4. Technology integration supports reconciliation, customer support, user experience, and cardholder benefits.

    Effective execution depends on transparent pricing, precise settlement timing, and operational controls that minimize exceptions while preserving payout speed and predictability globally.

    Card Network and BIN Setup Basics

    At the network layer, virtual card issuing begins with selecting the appropriate card scheme and configuring the bank identification number (BIN) architecture that governs authorization routing, geographic acceptance, merchant category controls, and settlement behavior. These decisions determine where transactions can clear, how interchange is applied, and which issuer processor relationships support real-time provisioning.

    Within remittance platforms, card network fundamentals include scheme participation rules, tokenization compatibility, cross-border acceptance parameters, and dispute workflow alignment.

    BIN setup essentials cover issuer identification ranges, domestic versus international usage flags, currency support, authorization velocity settings, and decline code mapping. A well-structured BIN strategy improves transaction approval rates, supports controlled spending environments, and reduces operational friction across multiple corridors.

    It also enables scalable program segmentation for consumer, payroll, or disbursement use cases.

    How KYC and AML Work for Virtual Cards

    Effective KYC and AML controls for virtual cards begin with rigorous customer identification, beneficial ownership verification, and risk scoring before any card credentials are issued or loaded.

    Within remittance platforms, KYC processes align customer onboarding with AML regulations through documented identity verification, sanctions screening, and jurisdictional risk assessment.

    Core compliance measures typically include:

    1. Collection and validation of customer records and ownership data
    2. Screening against sanctions, PEP, and adverse media databases
    3. Ongoing transaction monitoring for unusual velocity, geography, or funding patterns
    4. Secure retention of audit trails supporting regulatory review

    These controls support fraud prevention, data security, and program governance without delaying issuance.

    Operators must also address regulatory challenges, including cross-border rule variation, recordkeeping standards, and threshold-based escalation requirements across multiple supervisory regimes and banking partners.

    How Remittance Platforms Manage Fraud Risk

    Remittance platforms manage fraud risk through a layered control framework centered on real-time transaction monitoring, identity verification controls, and suspicious activity detection.

    These mechanisms are designed to identify anomalous payment behavior, validate user legitimacy, and contain exposure before funds are disbursed or card activity escalates. Their effectiveness is closely tied to rule calibration, data quality, and timely case escalation within the platform’s compliance and risk operations.

    Real-Time Transaction Monitoring

    Most modern remittance platforms rely on real-time transaction monitoring to identify anomalous payment behavior before funds are settled or withdrawn.

    These systems apply data analytics and technological integration to strengthen fraud prevention while preserving transaction efficiency and user experience.

    Monitoring frameworks typically support regulatory compliance, cost management, and customer support through automated alerting and exception workflows.

    Key capabilities include:

    1. velocity checks across cards, devices, corridors, and merchants;
    2. rules-based screening for unusual amounts, timing, and geolocation shifts;
    3. behavioral scoring models informed by market trends and historical activity;
    4. case escalation that prioritizes high-risk events for rapid intervention.

    Used effectively, continuous monitoring provides competitive advantage by reducing loss exposure, limiting operational disruption, and improving confidence in instant virtual card disbursement at scale across diverse payout networks globally.

    Identity Verification Controls

    Strengthening fraud defenses begins with identity verification controls that confirm whether a sender, recipient, or cardholder is legitimate before a transaction is approved or a virtual card is issued.

    Remittance platforms apply layered identity verification methods, combining user authentication techniques with document validation processes to establish a reliable customer profile.

    These controls often include biometric verification systems, liveness checks, device binding, and sanctions screening to support fraud prevention measures without delaying disbursement.

    Institutions also align onboarding workflows with compliance protocols and regulatory adherence practices, ensuring customer due diligence, KYC accuracy, and record retention standards are consistently met.

    In parallel, risk assessment strategies classify users by jurisdiction, transaction purpose, and funding source, allowing verification intensity to be calibrated appropriately while preserving operational efficiency, issuer trust, and cross-border program integrity overall.

    Suspicious Activity Detection

    Once identity has been established, ongoing suspicious activity detection monitors how accounts, transfers, and virtual card transactions behave over time to identify fraud patterns that static onboarding checks cannot capture.

    1. Transaction analysis evaluates velocity, value, geography, and merchant category indicators.
    2. Behavioral profiling establishes baselines for sender and recipient activity, enabling anomaly detection.
    3. Machine learning models strengthen fraud detection by scoring deviations and triggering alert systems.
    4. Compliance measures combine data encryption, user authentication, and escalation workflows for risk management.

    These controls help remittance platforms detect account takeover, mule activity, synthetic identities, and card misuse before losses expand.

    Effective monitoring also supports audit readiness, regulatory reporting, and operational response by prioritizing suspicious events for investigation and timely intervention across payment flows.

    Which Fees Drive Virtual Card Payout Costs

    Cost structure determines whether virtual card payouts remain an efficient disbursement rail or become a margin-intensive service line. Core fee structures typically include issuer setup fees, network assessments, processor markups, and authorization expenses tied to payout processing.

    Interchange treatment, depending on program design and merchant category acceptance, can also shape transaction costs materially.

    Additional cost drivers arise from cross-border settlement, foreign exchange spreads, and currency conversion mechanics applied between funding and recipient spending currencies. Compliance screening, fraud controls, API usage, and reconciliation tooling add operational expenses that platforms must absorb or pass through as service charges.

    Hidden fees may emerge through minimum commitments, inactive card balances, chargeback handling, or exception management. The aggregate effect of these inputs determines unit economics, pricing flexibility, and ultimately platform margins across recipient corridors and use cases.

    What Can Delay Instant Card Delivery

    Several operational and control-layer dependencies can delay ostensibly instant virtual card delivery, even when card issuance is fully API-enabled. Common delivery challenges typically emerge from interdependent checks, external connectivity, and downstream authorization timing, all of which affect user experience.

    1. Verification delays arise when identity, sanctions, or fraud-screening engines trigger manual review because of compliance issues or regulatory hurdles.
    2. System inefficiencies and technical glitches within issuer processors, orchestration layers, or tokenization services create operational bottlenecks.
    3. Network disruptions across card networks, SMS gateways, or mobile app infrastructure can interrupt provisioning and customer notification flows.
    4. Currency fluctuations may force rate refreshes or limit recalculations, especially in cross-border remittance corridors, delaying approval and card funding.

    Even milliseconds matter when sequential dependencies accumulate under load during peak transaction periods globally.

    How to Choose a Virtual Card Issuing Partner

    How should a remittance platform evaluate a virtual card issuing partner when delivery speed, compliance integrity, and cross-border scalability must operate in parallel?

    Effective partner selection requires assessment across operational, technical, and jurisdictional dimensions. The issuer should demonstrate strong regulatory compliance, resilient controls, and proven program management in multiple markets.

    Decision criteria also include technology compatibility with existing payout infrastructure, API maturity, and the ability to minimize integration challenges. Cost considerations should extend beyond interchange and setup fees to FX mechanics, dispute handling, and funding workflows.

    User experience matters, particularly card provisioning speed, wallet readiness, and recipient transparency. Customer support quality, service-level commitments, and incident responsiveness influence continuity.

    Finally, scalability options should be validated through processing capacity, BIN sponsorship flexibility, and expansion readiness for new corridors and volumes.

    Frequently Asked Questions

    Can Recipients Withdraw Cash From Virtual Remittance Cards?

    Yes, recipients can sometimes withdraw cash from virtual remittance cards, provided ATM access is enabled. Availability depends on card security protocols, transaction limits, issuer policies, PIN provisioning, and local network acceptance for cash-out functionality.

    Do Virtual Remittance Cards Affect Recipients’ Credit Scores?

    No—despite apocalyptic fears, virtual remittance cards rarely affect recipients’ credit scores, as most are prepaid instruments lacking credit reporting. Credit impacts typically arise only with linked lending features, while robust card security remains operationally distinct.

    Can Virtual Cards Be Reused After the Initial Remittance Is Spent?

    Usually, they cannot be reused after the initial remittance is spent, unless the issuer enables reloadable functionality. Reusability depends on program design, virtual card security controls, transaction limits, and compliance requirements governing authorized subsequent transactions.

    Are Virtual Remittance Payouts Available in Rural or Low-Connectivity Areas?

    Yes, though availability may be somewhat uneven; virtual remittance payouts can reach areas with rural accessibility, provided recipients have minimal device access. However, connectivity challenges, agent-network limitations, and intermittent authentication infrastructure may materially constrain reliable usage.

    What Customer Support Is Available if a Virtual Card Is Lost?

    If a virtual card is lost, customer assistance typically includes immediate card suspension, secure identity verification, reissuance procedures, transaction review, and fraud monitoring. Support is commonly available through in-app chat, hotline services, email, or platform help centers.

    Final words

    The theory that virtual card issuing can redefine remittance trust appears well founded. By converting approved transfers into instantly usable digital payment credentials, platforms reduce settlement latency, expand emergency liquidity access, and improve recipient control at the point of need. Yet this advantage depends on disciplined fraud controls, issuer connectivity, and transparent pricing. Where execution is strong, virtual cards do more than accelerate payout—they strengthen confidence, satisfaction, and the emotional security that cross-border money movement is meant to provide.
  • How to Scale Online Spending Safely for Sellers in Qatar

    How to Scale Online Spending Safely for Sellers in Qatar

    You should tie daily budgets to verified ROAS and stable CPA thresholds, increase spend incrementally, and cap audience frequency to avoid saturation. Verify tracking with pixels and server-side confirmations, test localized creatives and landing pages, and prioritize SKUs with strong margins and low returns. Implement fraud detection, OTP order validation, and chargeback monitoring with stop-loss rules. Use A/B tests and holdouts to prove incremental lift before scaling — keep going to see detailed steps and templates.

    Key Takeaways

    • Verify tracking accuracy (pixels, server-side events, and payment confirmations) before increasing ad spend to ensure true performance measurement.
    • Set incremental budget increases tied to stable CPA or target ROAS thresholds and pause when thresholds breach.
    • Prioritize profitable SKUs with predictable inventory, low returns, and localized creatives for Qatar-specific language and cultural fit.
    • Implement fraud detection (IP reputation, device fingerprinting, OTPs) and server-side order validation to reduce chargebacks.
    • Establish dashboards, threshold alerts, and owner responsibilities to monitor KPIs, cash flow risk, and stop-loss rules.

    Quick Checklist: Safe-Scaling for Qatar Sellers

    Start with these seven checks to scale ad spend in Qatar without blowing your ROI: verify tracking accuracy (pixels, server-side events, and payment confirmations), confirm audience reach and creative frequency caps to avoid saturation, set incremental budget increases tied to stable CPA or ROAS thresholds, test localized creatives and landing pages for language and cultural fit, audit bid strategies and dayparting against peak local traffic, ensure inventory and fulfillment can absorb higher orders, and monitor chargeback/fraud rates with automated alerts—run this checklist weekly and only push more budget when each metric stays within predefined acceptable ranges.

    You’ll align spend with market trends and customer behavior signals, validate payment options and logistics solutions, and use competitor analysis to benchmark bids.

    Track social proof and trust signals to boost conversion confidence, pilot influencer partnerships where ROI is measurable, and adopt emerging technologies for attribution accuracy. Localized strategies keep scale efficient.

    A Throwaway Card for the Web’s Rougher Corners

    There’s a whole category of online spending that doesn’t deserve your real card. A practical friend keeps a throwaway card purely for those low-trust transactions. She recommended the Card29 prepaid online card, and it became our internet buffer. For dodgy checkouts, unknown sellers, and one-off impulse buys, we use a disposable virtual card and keep our credit card out of it entirely. A dedicated VCC for the web’s rougher corners is the small habit that heads off big problems.

    Set Goals and KPIs Before Raising Ad Spend

    Before you ramp budgets, define specific goals and KPIs that map directly to profit—think target CPA, ROAS, LTV:CAC ratio, and incremental revenue per campaign—so every spend increase is tied to measurable business outcomes.

    You’ll ensure goal alignment across marketing, sales, and finance, and use performance metrics to judge whether scaling moves the needle on margin, not just traffic. Set timebound targets, decide which metrics trigger scale pauses, and assign ownership for reporting.

    1. Tie each campaign to a primary KPI and a secondary safeguard metric (e.g., CPA primary, conversion rate safeguard).
    2. Establish threshold triggers for scale/stop decisions based on real results, not projection.
    3. Build a dashboard that shows profit impact and short-term variance for daily reviews.

    Calculate Safe Ad Budgets: ROAS, CAC, Payback

    Anyone scaling paid channels needs a clear formula for how much you can spend without destroying margin: calculate target ROAS that covers product gross margin plus operating costs, determine acceptable CAC given your LTV and payback window, and convert those into daily and campaign-level budgets that respect conversion volatility and testing burn.

    You’ll compute target ROAS = (gross margin – overhead share)⁻¹ and cap CAC so payback occurs within your chosen months.

    Translate those targets into ad budget strategies: set conservative daily spending limits per campaign, allocate incremental increases tied to stable conversion cohorts, and model worst-case CAC scenarios.

    Track performance weekly, pause tests that breach spending limits, and reinvest only when ROAS and payback metrics consistently meet thresholds.

    Choose SKUs to Scale First: Product–Market Fit Rules

    Now that you’ve set ROAS and CAC ceilings, picking which SKUs to scale becomes a numbers game: prioritize products that hit profitability thresholds with consistent conversion behavior.

    You’ll use product selection guided by market alignment and competitive analysis, filter by sales performance and customer feedback, and validate via demand forecasting. Favor SKUs with clear pricing strategy margins, predictable inventory management, and strong brand positioning signals.

    1. Choose SKUs with steady sales performance, low return rates, and positive customer feedback that indicate product–market fit.
    2. Prioritize items where competitive analysis shows defensible positioning and pricing strategy supports planned ROAS increases.
    3. Confirm demand forecasting and seasonal trends justify increased spend without inventory strain, ensuring healthy CAC payback and scalable margins.

    Build a Testing Roadmap: Creative, Audience, Funnel

    When you build a testing roadmap, structure experiments around creative, audience, and funnel variables so each test isolates impact on ROAS and CAC. Prioritize high-confidence hypotheses informed by past performance data and expected lift. Set clear success metrics (statistical significance thresholds, minimum detectable effect, and payback period), and sequence tests to validate creative winners, scale audience segments, then optimize funnel touchpoints to protect margins as spend grows.

    You’ll run disciplined creative brainstorming to generate creative variations and follow creative guidelines for format, length, and CTA. Use audience segmentation and audience insights to target meaningful cohorts, track audience behavior, and measure audience engagement.

    Map funnel stages, apply funnel analysis, and deploy testing methodologies with testing tools. Define testing frequency, monitor performance metrics, and make campaign adjustments tied to ROI.

    Segment Qatar Audiences and Localize Messaging

    Because Qatar’s market is small but highly segmented, you should map distinct audience cohorts—by nationality, language (Arabic vs. English), income, age, and expat status to quantify audience preferences and digital behaviors.

    Use data to define messaging tone, communication styles, and trust factors that drive conversions. Prioritize localized content that respects cultural nuances and aligns with purchasing motivations and seasonal trends.

    1. Segment by social media habits and digital behaviors to tailor messaging tone and creative tests.
    2. Create localized content variants that reflect language, cultural nuances, and trust factors; measure CTR and CPA by cohort.
    3. Align offers to purchasing motivations and seasonal trends; track ROAS and adjust bids per cohort.

    Iterate fast: split-test, analyze, and reallocate spend to highest-ROI segments.

    Choose Ad Channels in Qatar: Google, Meta, TikTok, Marketplaces

    You should pick channels based on targeting precision and reach — Google for intent, Meta for granular demos, TikTok for younger reach, and local marketplaces for high-conversion shoppers.

    Compare CPMs, CPCs, and conversion rates to model cost-efficiency and projected ROI for each channel.

    Then allocate budget dynamically to the channels that deliver the best incremental return per dirham.

    Channel Targeting & Reach

    As you scale online spending in Qatar, select channels based on audience signals, CPA benchmarks, and incremental reach potential rather than personal preference.

    Use audience segmentation and competitive analysis to map where users live—Google for intent, Meta for social depth, TikTok for discovery, marketplaces for purchase intent. Leverage analytics tools and performance metrics to measure reach, frequency, and overlap.

    1. Allocate budget allocation by channel optimization: test creative formats, placements, and engagement strategies, then reassign spend to incremental reach.
    2. Monitor platform diversity to prevent saturation; prioritize channels showing incremental, non-overlapping reach.
    3. Use market trends and A/B tests to refine targeting windows, devices, and bid strategies, keeping ROI and scalable growth in focus.

    Cost Efficiency & ROI

    Having picked channels for reach and audience fit, now align spend to cost efficiency and ROI by tracking CPAs, LTV, and incremental ROAS across Google, Meta, TikTok, and marketplaces.

    You’ll run a rigorous cost analysis per channel, combining performance metrics and expense tracking to reveal true customer acquisition costs and channel-level margins.

    Use budget allocation rules that prioritize channels with positive incremental ROAS while enforcing spending limits where CPAs exceed LTV-derived thresholds.

    Build financial forecasting models that simulate scaling scenarios and stress-test your investment strategy against seasonality and supply constraints.

    Regular profitability assessment—weekly dashboards and cohort-level retention—lets you reassign spend quickly.

    Follow data-driven signals, cut waste, and reinvest gains into the highest-yield channels to grow safely and predictably.

    Craft Compliant, Culturally Appropriate Ad Creatives

    When ads respect platform policies and local norms, they’ll scale with fewer pauses and higher ROI—so build creatives that pass compliance checks and resonate culturally from day one.

    You’ll reduce risk and improve CTR by applying creative guidelines tied to compliance standards and regulatory awareness. Use audience insights and A/B tests to prove which messages drive conversions while preserving content authenticity and ethical advertising.

    1. Local partnerships: vet translations, imagery, and influencers to protect brand reputation and ensure message alignment with cultural sensitivity.
    2. Data-led templates: standardize assets that meet platform creative guidelines and shorten approval cycles.
    3. Compliance checklist: embed regulatory awareness into briefs, tracking rejection causes to optimize ad spend and lift ROI.

    Design High-Converting Landing Pages for Qatar Shoppers

    To convert Qatar shoppers at scale, prioritize landing pages that load fast, speak Arabic and English fluently, and reflect local UX expectations—mobile-first designs with under 3s load times boost conversion rates by up to 20% in MENA markets.

    You’ll focus on landing page optimization that reduces friction: clear CTAs in both languages, localized trust signals (Qatari payment options, certifications), and concise social proof.

    Measure bounce, time to first byte, and conversion per channel to attribute ROI accurately. Optimize forms for one-handed mobile use and prefill where possible to lift completion rates.

    Balance visual hierarchy and cultural norms to increase perceived relevance. Every design change should aim to improve user experience metrics that drive revenue and lower acquisition costs.

    Run A/B Tests, Holdouts, and Funnel Experiments

    Because controlled experiments reveal what actually moves the needle, you should treat A/B tests, holdouts, and funnel experiments as your primary toolset for scaling online spending safely.

    You’ll apply experiment design principles to isolate variables, use A/B testing strategies to validate creatives and offers, and rely on statistical significance evaluation to trust results.

    Use holdout group analysis to measure baseline conversion lift and avoid attribution bias. Funnel optimization techniques will target drop-off points with user behavior insights, prioritizing changes by expected ROI.

    Maintain testing frequency guidelines to balance speed and power, and institute data driven decision making—only scale channels that show repeatable lift. Track cost per incremental conversion and stop tests that lack meaningful impact.

    1. Define hypothesis, metric, and sample size.
    2. Run segmented tests; analyze holdouts.
    3. Optimize funnels, iterate by ROI.

    Use Incremental Lift Tests Before Broad Scaling

    Don’t blast budget wide after a winning creative—run small-scale A/B lift tests first to measure true incremental ROI.

    You’ll increase spend gradually only when lift is statistically significant, so you avoid scaling noise that erodes margins.

    This staged approach preserves unit economics while giving clear signals for confident, profitable growth.

    Small-Scale A/B Tests

    Before you roll out a major budget increase, run small-scale A/B tests that measure incremental lift so you can quantify the exact ROI of a change. You’ll use A/B testing strategies and control groups to isolate effects, make data driven decisions, and protect spend.

    1. Define clear performance metrics (conversion rate, CPA, LTV) and run variant comparisons long enough to reach statistical significance, so audience insights are reliable.
    2. Keep tests small and focused on user experience tweaks—copy, CTA, creative—so you can attribute lift and model ROI without broad exposure.
    3. Analyze results with cohort breakdowns, funnel impact, and cost per incremental conversion to decide whether scaling preserves return and meets growth targets.

    Gradual Budget Increases

    After you’ve validated lifts with small A/B tests, scale budgets in measured increments and use incremental lift testing to confirm that additional spend sustains the same return profile.

    You’ll want clear budget allocation strategies: allocate incremental spend to the top-performing segments, hold control groups steady, and track lift per incremental dollar.

    Use gradual increase methods like 10–20% weekly raises or doubling only after consistent ROI signals. Measure marginal cost per acquisition, incremental revenue, and statistical significance at each step.

    If ROI drops, pause increases and reassign spend to better-performing cohorts. Document each test’s duration, sample size, and confidence intervals so you can replicate winners.

    This disciplined, data-driven approach preserves profitability while unlocking scalable growth.

    Protect Margins With Dynamic Pricing Rules

    When you scale ad spend, dynamic pricing rules keep margins intact by automatically adjusting prices in response to cost changes, competitor moves, and demand signals. You’ll use dynamic pricing strategies and margin protection techniques to protect ROI as CPCs rise. Set rule thresholds tied to CPA, profit per unit, and conversion rate, and let automation act faster than manual updates.

    1. Tie price floors/ceilings to real-time CPA and target margin so bids don’t erode profitability.
    2. Use competitor index triggers to incrementally raise/lower prices while preserving volume.
    3. Apply demand elasticity models to increase prices on high-intent traffic and cut on low-converting segments.

    Monitor outcomes with A/B tests and rolling dashboards to quantify lift and preserve growth.

    Control Inventory Risk: Safety Stock and Reorder Points

    Because stockouts and overstock both bleed ROI, you should treat safety stock and reorder points as performance levers tied to conversion rates and ad spend efficiency.

    Use demand forecasting and historical sales variance to calculate safety stock so your reorder strategy minimizes lost sales without inflating carrying costs.

    Run risk assessment by SKU: quantify lead-time variability, supplier reliability, and promotional uplift, then set reorder points that trigger replenishment before conversion drops.

    Monitor inventory turnover and adjust safety levels as velocity changes; faster turnover lowers required buffers, slower turnover increases holding risk.

    Integrate supply chain signals into your inventory management system for automated alerts and continuous stock optimization.

    Measure impact on conversion and CAC to close the loop between inventory and ad spend.

    Manage Shipping and Returns Cost-Effectively in Qatar

    Inventory decisions directly affect your shipping and returns economics, so you’ll want to align fulfillment choices in Qatar with both margin targets and customer experience KPIs.

    Use data to pick shipping solutions that balance speed and cost; measure service level and delivery options by on-time rate and cost-per-order.

    Standardize packaging standards to reduce damage rates and return volumes, and publish clear return policies to set expectations and lower reverse-logistics cost.

    Ensure cost transparency across channels so ROI per sale is visible.

    1. Negotiate local partnerships to cut last-mile costs and improve service level metrics.
    2. Optimize return policies to discourage costly frivolous returns while preserving conversion.
    3. Automate customer communication for tracking, returns authorization, and cost allocation.

    Comply With Qatari Ecommerce, Customs, and Consumer Law

    If you want to scale online spending in Qatar without regulatory setbacks, map applicable ecommerce, customs, and consumer laws to your unit economics and reporting cadence—then treat compliance as a predictable cost center rather than an afterthought.

    You’ll quantify duties, VAT, and licensing into CAC and LTV models, and set thresholds that trigger escalation when margins dip below targets.

    Build reporting that ties order-level data to customs declarations and returns rates so you can forecast cash flow and buffer reserves for fines or inspections.

    Adopt standard operating procedures that reflect Qatari ecommerce regulations and prioritize consumer protection to reduce disputes and chargebacks.

    Measure compliance ROI: fewer holds, faster deliveries, improved conversion, and lower refund expense per acquisition.

    Detect and Prevent Ad Fraud, Click Fraud, and Fake Orders

    You should constantly monitor traffic patterns and conversion metrics to spot anomalies that signal ad or click fraud.

    Use thresholds and automated rules to block suspicious IPs, bots, and low-quality referrers before they skew ROI.

    Pair real-time detection with order-validation checks to stop fake orders and preserve ad spend efficiency.

    Identify Suspicious Traffic

    Start by instrumenting your traffic so you can quantify anomalies in clicks, conversions, and order values—then treat deviations as lead indicators rather than noise.

    Use analytics tools to map traffic patterns and spot traffic anomalies fast. Correlate sudden spikes with source attribution so you can flag suspicious sources and prioritize investigation.

    1. Monitor user behavior and session metrics: short sessions with high clicks are red flags; pair this with bot detection signals and IP/device clustering.
    2. Run automated verification methods: CAPTCHA, fingerprinting, and rate limits to validate intent before costly conversions and ad spend.
    3. Triangulate data for ROI decisions: combine conversion quality scores, source cost, and post-click LTV to decide whether to pause, whitelist, or further probe sources.

    Block Fake Orders

    Having flagged suspicious sources and behavior, lock down the funnel to prevent fake orders from inflating spend and skewing ROI metrics.

    You’ll implement fraud detection layers: IP reputation, device fingerprinting, velocity rules, and anomaly scoring to block automated clicks and bot-driven orders in real time.

    Tie ad platforms to your backend so conversions require server-side confirmation before counting toward campaign KPIs.

    Use multi-step order verification — email/SMS OTPs, payment authorization checks, and address validation — to cut chargebacks and wasted CPA.

    Monitor false positive rates and conversion lift to balance protection with growth; aim for minimal friction while keeping fraudulent orders under a fixed threshold.

    Report savings as recovered ROAS and reduced CAC to justify investments in prevention.

    Set Refund, Chargeback, and Verification Policies to Limit Abuse

    When customers can exploit lenient refund and verification gaps, fraud eats margin and skews acquisition ROI.

    So you should define strict, measurable policies that deter abuse while preserving conversion. Use data-driven refund management and chargeback prevention tactics: quantify thresholds, timelines, and acceptable evidence to reduce disputes and lower processing costs.

    1. Define verification processes tied to risk assessment and transaction monitoring — require step-up authentication for high-risk orders to cut fraud rates without blocking legitimate customers.
    2. Implement policy enforcement with clear SLAs, automated flags, and escalation paths to resolve claims fast and protect CLTV and unit economics.
    3. Pair abuse mitigation with customer education: publish transparent return rules and dispute guides to reduce friction, decrease chargebacks, and improve acquisition ROI.

    Scale Ops: Automation, Partners, and Stop-Loss Rules

    Mitigate operational risk at scale by automating repeatable workflows, partnering strategically, and enforcing stop-loss rules that protect margin and cash flow.

    You’ll deploy automation tools to reduce manual errors and boost operational efficiency, tracking performance metrics like conversion rate, CPA, and LTV to guide scaling strategies.

    Tap partner networks for regional fulfillment, payments, and compliance measures, choosing partners with proven ROI and clear SLAs.

    Implement stop-loss rules tied to spend, return rates, and unit economics so you halt campaigns before losses compound.

    Combine risk management dashboards and financial safeguards—reserve buffers, credit limits, and dispute protocols—to preserve cash flow.

    Continuously iterate based on metrics; that disciplined, data-driven approach sustains scalable, profitable growth.

    Final words

    You’ve got a data-first playbook: set clear KPIs, model ROAS/CAC payback, and pick SKUs with proven product–market fit before you crank spend. Test creatives, audiences, and funnels methodically, lock down compliance with Qatari law and customs, and tighten verification to stop fraud and fake orders. Automate ops, set stop-loss rules, and partner smartly—think of it like a steam engine powering predictable ROI growth: measured, repeatable, and built to scale safely.

  • How to Choose a Payment Gateway Service Provider in Bangladesh

    How to Choose a Payment Gateway Service Provider in Bangladesh

    Introduction

    The growth of digital commerce in Bangladesh has increased the need for secure and reliable online payment systems. Businesses now depend on payment gateway service providers to process transactions across e-commerce platforms, mobile applications, subscription services, and digital marketplaces.

    A payment gateway service provider enables businesses to accept payments through debit cards, credit cards, mobile financial services, internet banking, and digital wallets. The system ensures secure data transfer between customers, merchants, and financial institutions.

    Just as Industrial infrastructure services in Western Australia provide structured systems that support industrial operations, payment gateway service providers create the digital infrastructure that supports secure and efficient financial transactions.

    What Is a Payment Gateway Service Provider

    payment gateway service provider in Bangladesh service provider is a technology company that facilitates online transactions by securely transferring payment data from customers to banks and financial networks.

    The system encrypts sensitive information, verifies transaction details, and ensures successful fund transfer. It acts as a secure bridge between all parties involved in the transaction.

    Modern providers support multiple payment methods through a unified platform, helping businesses simplify payment operations.

    Why Choosing the Right Provider Matters

    Selecting the right payment gateway is important for business performance and customer satisfaction.

    A reliable provider ensures fast transaction processing, high security standards, and minimal downtime. Poor payment systems can lead to failed transactions, abandoned carts, and loss of customer trust.

    Businesses that invest in stable payment infrastructure can improve operational efficiency and increase conversion rates.

    The importance of reliable systems is similar to Industrial infrastructure services in Western Australia, where operational continuity depends on stable and well-designed infrastructure systems.

    Key Factors to Consider When Choosing a Payment Gateway

    Security Standards

    Security is one of the most important factors in selecting a payment gateway service provider.

    Modern systems use encryption, tokenization, fraud detection tools, and multi-factor authentication to protect financial data.

    A secure system reduces fraud risks and protects customer trust.

    Supported Payment Methods

    A good payment gateway should support multiple payment options.

    These include debit cards, credit cards, mobile financial services, internet banking, digital wallets, and QR-based payments.

    More payment options increase customer convenience and improve transaction success rates.

    Transaction Speed

    Fast transaction processing improves customer experience.

    Most modern gateways complete payment authorization within a few seconds.

    Slow processing can lead to cart abandonment and reduced sales.

    Integration Capability

    The provider should offer easy integration with websites, mobile applications, and e-commerce platforms.

    API-based integration helps businesses connect payment systems with minimal technical effort.

    Settlement Time

    Settlement time refers to how quickly funds are transferred to a merchant’s bank account.

    Faster settlement improves cash flow and financial stability for businesses.

    Reporting and Analytics

    Advanced reporting tools help businesses track transactions, monitor revenue, and analyze customer behavior.

    These insights support better financial decision-making.

    Features of a Reliable Payment Gateway Provider

    High Availability

    Reliable providers ensure system uptime and uninterrupted transaction processing.

    This reduces payment failures and improves customer satisfaction.

    Scalable Infrastructure

    A scalable system can handle increasing transaction volumes as the business grows.

    This is essential for e-commerce platforms and high-traffic applications.

    Fraud Prevention Systems

    Fraud detection tools monitor transactions in real time and identify suspicious activity.

    This reduces financial risks and protects both businesses and customers.

    Multi-Currency Support

    Some providers support international payments, allowing businesses to serve global customers.

    This feature is important for export-oriented e-commerce businesses.

    The importance of scalable and secure infrastructure reflects Industrial infrastructure services in Western Australia, where systems are designed to support long-term operational efficiency.

    Benefits of Using a Professional Payment Gateway Provider

    Businesses gain several advantages when using a professional payment gateway service provider.

    It simplifies online payment collection and reduces manual processing.

    It improves transaction security and customer trust.

    It supports multiple payment channels in a single system.

    It helps businesses expand into new markets and customer segments.

    It provides detailed financial reports that improve business management.

    These benefits contribute to improved efficiency and long-term business growth.

    Industries That Use Payment Gateway Services

    Payment gateway solutions are used across multiple industries in Bangladesh.

    E-commerce platforms use them for online product sales.

    Educational institutions collect tuition fees and online course payments.

    Healthcare providers process appointment and treatment payments.

    Travel agencies manage ticket bookings and reservations.

    Subscription-based platforms handle recurring payments.

    Service-based businesses use payment gateways for invoicing and billing.

    This widespread usage highlights the importance of digital payment infrastructure in modern business operations.

    Security Technologies Used in Payment Gateways

    Encryption

    Encryption protects sensitive payment data during transmission between systems.

    Tokenization

    Tokenization replaces financial data with secure digital tokens.

    Fraud Detection

    Fraud monitoring systems analyze transaction patterns and detect suspicious activity.

    Authentication Systems

    Authentication verifies user identity before completing transactions.

    These technologies ensure safe and reliable payment processing.

    The focus on security aligns with Industrial infrastructure services in Western Australia, where safety and system integrity are essential for operational performance.

    Common Mistakes to Avoid When Choosing a Provider

    Some businesses make mistakes when selecting a payment gateway service provider.

    Choosing a provider with limited payment options can reduce customer convenience.

    Ignoring security features can increase financial risk.

    Selecting a system with slow settlement times can affect cash flow.

    Failing to consider scalability can limit future business growth.

    Careful evaluation helps businesses avoid operational challenges.

    Future of Payment Gateway Services in Bangladesh

    Payment gateway services are evolving rapidly due to technological advancement.

    Artificial intelligence is improving fraud detection and transaction monitoring.

    Real-time payment systems are reducing settlement delays.

    Digital wallets and QR payments are becoming more widely used.

    Cloud-based infrastructure is improving scalability and performance.

    These developments are expected to make payment systems faster, safer, and more efficient.

    The continuous improvement of digital infrastructure reflects Industrial infrastructure services in Western Australia, where long-term investment supports innovation and operational reliability.

    FAQ

    What is a payment gateway service provider?

    A payment gateway service provider is a company that enables businesses to securely process online payments from customers.

    Why is choosing the right payment gateway important?

    It ensures secure transactions, improves customer experience, and supports business growth.

    What payment methods should a gateway support?

    It should support cards, mobile financial services, internet banking, digital wallets, and QR payments.

    Are payment gateways secure?

    Yes. They use encryption, tokenization, fraud detection, and authentication systems to protect transactions.

    Can small businesses use payment gateways?

    Yes. Payment gateway solutions are available for startups, SMEs, and large enterprises.

    What affects payment gateway performance?

    Security, transaction speed, integration quality, settlement time, and system reliability affect performance.

    Conclusion

    Choosing the right payment gateway service provider in Bangladesh is essential for secure and efficient digital transactions. A reliable system improves customer trust, supports multiple payment methods, and enhances business performance.

    As digital commerce continues to grow, businesses need strong and scalable payment infrastructure to remain competitive. Similar to Industrial infrastructure services in Western Australia, which provide stable systems for industrial operations, payment gateway providers deliver the foundation for secure, reliable, and efficient financial transactions. Businesses that select the right provider can achieve better operational efficiency, improved customer satisfaction, and long-term growth.

  • The Pros and Cons of Virtual Credit Cards for Buyers in Portugal

    The Pros and Cons of Virtual Credit Cards for Buyers in Portugal

    Virtual cards give you tighter control and stronger fraud protection for online purchases in Portugal — you get disposable or limited-use numbers, real-time alerts, and masked details that keep shops from seeing your main account. Major banks and fintechs offer instant setup, but expect occasional merchant rejections, 3D Secure or AVS hiccups, and headaches with some subscriptions or rentals. They’re great for one-offs and safer shopping; keep a backup card handy and continue to learn how to use them best.

    What Is a Virtual Card in Portugal?

    A virtual card in Portugal is a digital-only payment card you use for online or phone purchases without a physical plastic card. Banks and fintechs generate it instantly within an app or web portal, providing a card number, expiry date, and security code that work like a regular card but can be single-use, limited to a merchant, or set with spending limits for extra control.

    You’ll manage the card from your smartphone, activating, freezing, or deleting it in seconds. That gives you strong digital security by isolating transactions and reducing exposure of your main account details.

    You’ll enjoy payment convenience through instant issuance and tailored controls, making subscriptions, one-off buys, and international payments simpler while limiting fraud risk.

    Portuguese Banks & Apps That Offer Virtual Cards

    You’ll want to check both major Portuguese banks and digital-only providers to see who issues virtual cards and how they differ.

    Compare features like single-use numbers, spending limits, currency support, and fees to find the best fit.

    I’ll walk you through key banks and apps and a concise comparison of their card features.

    Major Portuguese Banks

    When you’re choosing a bank in Portugal, look for institutions that already integrate virtual cards into their mobile apps and online services; this keeps sign-up, card management, and spending controls simple and fast.

    Major Portuguese banks like Millennium bcp, Caixa Geral de Depósitos and Banco Santander Totta have added virtual-card features to leverage modern banking technology and strengthen digital security.

    You’ll find familiar apps let you generate single-use numbers, set limits, freeze cards and review transactions instantly. If you already bank with one of these incumbents, you’ll avoid switching providers while keeping oversight centralised.

    Check fees, compatibility with international merchants, and whether the app supports tokenisation for mobile wallets.

    Compare limits and customer support response times before you rely on a virtual card for regular online purchases.

    Digital-Only Providers

    If you prefer fully digital experiences over traditional banks, several Portuguese digital-only providers and fintech apps specialise in virtual cards and streamlined online payment tools.

    You’ll find apps that let you create single-use or controlled virtual cards inside digital wallets, so you can shop without exposing your main account.

    These providers often push fast onboarding, intuitive interfaces, and strong security features like tokenisation and real-time notifications.

    They suit you if you value convenience, spending control, and quick card management from your phone.

    Expect competitive fees and easy card freezing, though customer support can vary.

    Choose a provider that matches your comfort with app-first banking and integrates smoothly with your everyday digital wallets.

    • Excited about instant control?
    • Relieved by added safety?
    • Confident with quick freezes?
    • Frustrated if support lags?
    • Empowered by spending limits?

    Card Features Comparison

    Although digital-only apps and traditional banks both offer virtual cards, their feature sets can differ significantly. You’ll want to compare issuance types (single-use vs. reusable), custom spending controls, tokenisation and 3D Secure support, card lifecycle tools (instant freeze, expiry management, and easy replacement), and fee structures to pick the best fit for your habits and security needs.

    Look at major Portuguese banks and fintechs: many apps give instant issuance, per-transaction limits, and disposable numbers, while some banks bundle virtual cards with existing account services.

    Check security features like biometric access, real-time alerts, and tokenisation. Review usage statistics from providers if available to judge reliability and fraud rates.

    Finally, weigh costs, cross-border fees, and merchant acceptance before deciding.

    The Buffer That Made Online Spending Feel Safe

    For years we figured shopping online just meant trusting every site with our card. A friend who’d survived a fraud scare insisted otherwise. She recommended the Qwikvcc virtual credit card, and the change was instant. Every merchant draws on a unique prepaid card, each capped and disposable, while our bank account stays untouched. Treating a VCC as a buffer between you and the internet turns out to be one of the simplest security upgrades going.

    How Virtual Cards Cut Fraud and Protect Data

    You can limit exposure by using single-use or time-limited virtual numbers that stop working after a purchase.

    Masked card details mean merchants never see your real card info, so stolen data is useless.

    And with real-time transaction alerts you’ll spot and stop suspicious charges immediately.

    Limited-Use Numbers

    When you use a virtual card with a limited-use number, each transaction gets its own unique card details that expire after one payment or a short time window.

    You’ll see clear limited use benefits: stolen numbers aren’t reusable, merchants can’t store your live card, and automated fraud attempts fail quickly.

    But be aware of limited use drawbacks: one-time numbers can complicate refunds or recurring purchases if you don’t plan ahead.

    • Relief knowing thieves can’t reuse a number
    • Anger when a refund stalls because the number expired
    • Confidence in shopping at unfamiliar Portuguese merchants
    • Frustration if a subscription needs a permanent card
    • Peace of mind when your payment data isn’t broadly exposed

    Masked Card Details

    Because virtual cards replace your real card number with masked details, merchants and data breaches only ever see a throwaway identifier instead of your live account, cutting exposure and fraud risk.

    You’ll benefit from masked card security because each virtual number limits what’s stored by sellers and what criminals can reuse.

    Virtual card anonymity keeps your primary account and personal billing info out of merchant databases and reduces linkability across sites.

    When a token is compromised you can cancel or expire it without affecting other payments, so recovery is quick and contained.

    You should still monitor statements and use providers with strong authentication, but masked details make routine online shopping far safer by narrowing attack surfaces and containing breaches to disposable identifiers.

    Real-Time Transaction Alerts

    If a charge hits a virtual card, you’ll usually get an immediate alert so you can verify it on the spot and stop fraud before it spreads.

    Real time notifications pair with transaction monitoring so you see each swipe, online purchase, or subscription in seconds. You can flag unfamiliar charges instantly, freeze or cancel the virtual number, and provide clear evidence to your bank.

    That rapid loop cuts losses and reduces stress, since you won’t be guessing about when or how data was exposed. These alerts also limit merchant access to long-term card details, protecting future purchases and your identity.

    • Relief when a weird charge appears
    • Confidence to shop freely
    • Anger turned into action
    • Calm after blocking fraud
    • Trust restored with proof

    When Virtual Cards Fail: Merchant Rejection & Errors

    Although virtual cards cut fraud and simplify payments, you’ll still run into merchant rejections and processing errors that stop a purchase cold.

    You may face merchant compliance issues when a seller’s system can’t validate a one-time number or rejects unfamiliar BIN ranges, so always have a backup card.

    Transaction processing challenges — like 3D Secure mismatches, AVS failures, or tokenization gaps — can trigger declines even if funds are available.

    If an online checkout fails, retry with correct billing details, clear cached data, or contact the merchant to confirm they accept virtual or international BINs.

    Keep screenshots and transaction IDs for disputes, and reach out to your card issuer promptly to resolve authorization holds or request a reissue.

    Will Virtual Cards Break Your Subscriptions?

    If you use virtual cards for recurring services, you’ll need to check whether the merchant accepts them for ongoing billing.

    Ask how often your provider rotates card numbers and whether they offer a stable number or a long-lived token for subscriptions.

    Otherwise, a rotated or single-use number can cause failed payments and interrupted access.

    Recurring Billing Compatibility

    When you switch to virtual credit cards, recurring subscriptions can keep running—but you’ll need to set them up correctly. You’ll want to confirm each recurring payment uses the virtual card details or a linked token so subscription management stays seamless.

    Check billing flexibility options the merchant offers, because some services don’t accept temporary numbers. Test one subscription first to verify the user experience and avoid service interruptions.

    Keep records of renewal dates and amounts so you can update cards before expiry or cancellation.

    • Relief: no more fear of unexpected charges
    • Frustration: extra steps to update payment info
    • Confidence: control over where money goes
    • Anxiety: worries about failed renewals
    • Empowerment: better subscription management and clarity

    Card Number Rotation

    Because virtual cards can regenerate numbers regularly, you’ll want to know how rotation affects subscriptions and automated payments. You’ll get strong card security and fraud prevention because rotated numbers limit exposure if a merchant is breached.

    That can complicate subscription management: recurring billing often needs a stable number, so you’ll have to update merchants or use a persistent virtual number option.

    For online shopping and one‑off purchases, rotation boosts protection without extra effort, preserving transaction convenience.

    To keep usage flexibility, check if your provider offers controls for which cards rotate and which remain fixed, and use payment tracking tools to reconcile charges.

    Plan ahead: decide which subscriptions need a permanent card and which can use rotating numbers.

    Virtual Card Fees, Limits and FX in Portugal

    Though virtual cards cut fraud risk and simplify online payments, you’ll still face fees, spending limits, and currency conversion rules that affect their cost and convenience in Portugal.

    You should check virtual card fees—issuance, monthly, or per-transaction charges can add up. Transaction limits vary by provider: some let you set one-off caps, others impose daily or monthly ceilings that may block larger purchases.

    Foreign exchange handling matters if you buy from non-euro merchants; providers may apply markups or dynamic currency conversion. Compare effective exchange rates and whether your bank uses mid-market rates or adds a percentage.

    Read terms for refunds, cross-border fees, and replacement policies so you won’t be surprised.

    • Frustration when a card declines mid-checkout
    • Relief from lower fraud exposure
    • Anger over hidden fees
    • Comfort in clear limits
    • Anxiety about poor FX rates

    Best Everyday Uses for Virtual Cards

    If you want smarter, safer everyday spending, virtual cards fit a surprising range of routine purchases: subscriptions, one‑off online orders, meal delivery, and recurring services where you’d rather not share your real card details.

    You can use them for online shopping and subscription services to isolate vendors and limit exposure. They’re handy for travel bookings and event tickets when you want controlled authorizations, and for gift purchases so refunds don’t affect your main account.

    Use virtual cards in mobile apps for food delivery and digital services, or set temporary numbers for utility payments and other recurring bills.

    Keep one reserved for emergency expenses to avoid scrambling a physical card.

    Pick cards with easy management and clear expiry controls for optimal daily use.

    Poor Fits: When Not to Use a Virtual Card

    Virtual cards handle lots of everyday transactions well, but they aren’t the right tool for every payment. You should avoid them when a merchant needs a persistent card on file, when recurring subscriptions must survive token changes, or when refunds and disputes require the original long‑lived number.

    They can also complicate travel bookings or car rentals that preauthorize large holds, causing payment delays or rejection.

    • You feel trapped if a hotel won’t accept temporary numbers.
    • You panic when a car hire preauthorization fails at the counter.
    • You get frustrated when refunds go to a closed virtual account.
    • You worry about fraud risks if a merchant’s systems mishandle tokens.
    • You lose time untangling failed recurring payments.

    Set Up a Virtual Card (Step‑by‑Step)

    Before you start, gather your ID, a Portuguese billing address, and the cardless app or bank website you’ll use—this will make the process quick and error‑free.

    Open the app or site, sign in, and choose “create virtual card.” Verify your identity when prompted, using the ID and address.

    Select card limits: single‑use or reusable, spending cap, and expiry. Link the virtual card to your funding account and confirm.

    Note settings for notifications to track each charge—this boosts virtual card security and helps with transaction management.

    Test with a small purchase or merchant that supports virtual cards. Save the virtual card details securely in the app only; don’t email numbers.

    Destroy or cancel cards when you’re done.

    Checklist: Choosing the Right Virtual Card Provider

    Now that you’ve set up a virtual card and tested it, pick a provider that matches how you’ll actually use the card. Focus on provider reputation and scan user reviews to feel confident.

    Then compare security features and clear fee structures. Check customer support responsiveness, integration options with your apps, and mobile compatibility so things don’t break when you need them.

    Confirm transaction limits, card expiration policies, and whether ease of use is real in the app.

    • Imagine relief when customer support answers fast
    • Picture frustration avoided by transparent fee structures
    • Feel secure with strong security features in place
    • Enjoy convenience from smooth integration options
    • Trust grows when user reviews back the provider reputation

    Quick Decision Guide: Should You Use Virtual Cards in Portugal?

    Wondering if a virtual card fits your spending habits in Portugal? Ask whether you frequently shop online, travel, or need one-time payment controls.

    If you value extra security measures like disposable numbers and spending limits, virtual cards reduce fraud risk and simplify dispute handling.

    Consider merchant acceptance—some local services still prefer physical cards or MB WAY. Evaluate fees, currency conversion, and whether the provider offers seamless user experience on mobile apps and customer support in Portuguese.

    If you want tight control for subscriptions or cross-border purchases, virtual cards help.

    If you rely on in-person payments, cashbacks tied to physical cards, or need broad merchant compatibility, stick with traditional cards.

    Choose based on your typical transactions and comfort with digital tools.

    Frequently Asked Questions

    Can Virtual Cards Be Shared Between Family Members or Roommates?

    Yes — you can share virtual cards with family sharing tools some issuers offer, but you’ll face security concerns: you should set limits, monitor transactions, and only share with trusted roommates or relatives to avoid fraud or misuse.

    Do Virtual Cards Affect Mortgage or Loan Application Credit Checks?

    Like a shadow, virtual cards usually don’t show on credit reports, so they won’t directly affect mortgage or loan application credit checks. You should still do an impact assessment, since issuer reporting can influence credit scoring indirectly.

    Can I Use a Virtual Card to Receive Refunds or Chargebacks in Portugal?

    Yes — you can usually receive refunds and pursue chargebacks with virtual cards in Portugal; just check refund processing times and issuer chargeback policies, keep transaction records, and contact your card provider promptly if disputes or delays arise.

    Are Virtual Cards Covered by EU Consumer Protection Laws During Disputes?

    Yes — you’re generally protected: virtual card security doesn’t remove EU consumer rights, so you can pursue disputes, chargebacks, and refunds under EU rules, though specific coverage and bank procedures can affect how claims are handled.

    Can I Use Virtual Cards for Recurring Public Transport or NFC Payments?

    Absolutely — you can’t always use virtual cards for recurring public transport or NFC payments, but many issuers support them: virtual card benefits and security features shine for one‑off online payments, while contactless/subscription support varies by issuer.

    Final words

    Choose carefully: virtual cards can curb costly card-cloning, cut checkout confusion, and conceal credentials, but they can complicate continuous charges, confuse certain merchants, and create cancellation car-crashes. In Portugal, pick providers with plain policies, prompt portability, and robust protections. Try a temporary test, track transactions, and toggle limits. If subscriptions, recurring rentals, or refunds matter most, stick with standard cards—otherwise, switch to virtuals for secure, smart, streamlined spending.

  • Virtual Credit Cards in Turkey: Pay Online Without Currency Hassles

    Virtual Credit Cards in Turkey: Pay Online Without Currency Hassles

    You can use a Turkish virtual credit card to pay international sites and subscriptions in foreign currencies while keeping your real card details hidden and controlling spend limits to reduce fraud risk. Banks and fintechs like Garanti BBVA, İşbank, Akbank, Papara and Revolut Türkiye issue instant or disposable cards with expiry, merchant controls and freeze/unfreeze options. Expect FX markups and possible issuance or per‑use fees, but clear receipts and TRY settlement simplify reconciliation — keep going to learn practical setup and troubleshooting tips.

    What Is a Virtual Credit Card in Turkey and How It Works

    Although you mightn’t see a plastic card in your wallet, a virtual credit card in Turkey works like a regular card for online and contactless payments: your bank or fintech issues a unique card number, expiration date, and CVV that you use instead of your main card details.

    You’ll link that virtual card to your account or digital wallets app, set spending limits or single‑use parameters, and authorize transactions quickly. Merchants process payments as they’d with a physical card, but your real card info stays hidden, reducing fraud risk.

    You’ll monitor charges via mobile banking, freeze or delete the virtual number if something looks off, and enjoy improved transaction security without changing how you shop online.

    Quick Answer: Use a Virtual Card for Cross‑Border Payments

    If you need to pay or receive money across borders, using a virtual card can make cross‑border payments faster, safer, and often cheaper than traditional methods.

    You’ll link the virtual card to a digital wallet or bank app, then pay in foreign currencies without sharing your real card details. That reduces fraud risk and boosts payment security, since you can set single‑use numbers, limits, or expiration dates instantly.

    Transactions clear quickly, and currency conversion may be more transparent than invoice or wire fees. You’ll also avoid carrying physical cards and can control spending per merchant.

    For receiving funds, some services let you generate virtual cards tied to merchant accounts, simplifying reconciliation.

    Try one to streamline international online payments.

    The Setup That Made Our Online Buying Predictable

    Impulse spending online is easy when your full credit limit is one click away. A disciplined friend told us she caps herself by routing purchases through a virtual card platform with preset limits. She recommended Vizocard, and it brought a welcome sense of order to our spending. We decide the amount, load the prepaid card, and the ceiling is built in. There’s no way to overspend on a card that only holds what we put on it—the simplest kind of financial guardrail a VCC can offer.

    Which Turkish Banks & Fintechs Issue Virtual Cards : Limits & Features

    Curious which Turkish banks and fintechs let you create virtual cards and what limits or controls they impose? You’ll find major banks (like Garanti BBVA, İşbank, Akbank) and fintechs (Papara, iyzico, Revolut’s Türkiye options) offering virtual card benefits such as disposable numbers, spend controls, and instant issuance.

    Limits and features vary by provider:

    1. Daily/transaction limits — banks often set higher single‑payment caps; fintechs favor lower rolling limits you can adjust in-app.
    2. Controls — card freezing, merchant blocking, recurring‑payment toggles; some provide BIN‑level restrictions via banking partnerships.
    3. Validity & reloads — one‑time, time‑limited, or reloadable virtual cards; funding can come from accounts or linked cards.

    Check each issuer’s app for exact caps, KYC needs, and whether they support cross‑border BINs before you commit.

    How Fees, FX and TRY Settlement Work With Virtual Cards

    When you use a virtual card in Turkey, fees, FX handling and TRY settlement happen behind the scenes but directly affect what you pay and when funds move. So, it’s important you know the basics: banks and fintechs may charge issuance, monthly or per-transaction fees and a currency conversion margin if you pay in EUR, USD or other currencies.

    You’ll often see the merchant’s charge in its currency, then your provider converts to TRY using their rate and posts it to your account. Check fee schedules for upfront costs and FX markup; compare providers for lower spreads.

    Good providers show transaction transparency with clear receipts showing original currency, conversion rate and final TRY amount, so you can verify charges and dispute errors promptly.

    Get and Activate a Virtual Card (Step‑by‑Step)

    Get your virtual card quickly by signing up with a bank or fintech, completing any ID and verification steps, and choosing the card type and limits you need.

    You’ll then activate the card in-app or online; activation is immediate for most providers, giving you instant access to virtual card benefits and built-in security features.

    Follow these simple steps:

    1. Verify identity with your ID, selfie or e‑government credentials, and confirm contact details.
    2. Create or request a virtual card, select currency and notification preferences, then accept terms.
    3. Activate the card via SMS code, app confirmation, or one‑click activation and save the card details for secure use.

    After activation, test a small transaction to confirm everything works and note how security features protect your payments.

    Set Virtual Card Limits, Expiry & Merchant Currency

    Because virtual cards give you granular control, you should set spending limits, expiry dates, and merchant currency preferences before using them widely.

    Start by choosing a sensible limit per transaction and a daily or monthly cap so fraud or mistakes won’t drain your account.

    Pick expiry dates that match the planned purchase window — short for single buys, longer for recurring needs — and update them if plans change.

    Select merchant currencies to avoid unwanted conversion fees: lock to TRY for local merchants or to the merchant’s billing currency when you want predictable charges.

    These settings let you balance security and usage flexibility, reduce conversion surprises, and make it easy to revoke or adjust access when a vendor’s behavior or price changes.

    Virtual Cards for One‑Time Buys vs Subscriptions

    When you use a virtual card for a one‑time purchase, you can set a tight single‑transaction limit and short expiry to stop future charges.

    But if you try to pay for a subscription with a single‑use or highly restricted card, recurring payments can fail or be blocked by the merchant.

    You’ll need to weigh control and convenience when choosing settings for one‑offs versus ongoing bills.

    One‑Time Card Limits

    Sometimes a virtual one‑time card is exactly what you need: it lets you authorize a single purchase for a fixed amount and then immediately becomes unusable, protecting you from unexpected recurring charges.

    You’ll appreciate how one‑time card limits enforce secure transactions and bolster online privacy by capping exposure to merchants.

    You set the limit, so you control cost and risk. Consider common use cases:

    1. Small one‑off purchases where you want precise spending control.
    2. High‑risk vendors where limiting liability matters most.
    3. Trial offers or marketplaces that might retain card details.

    Keep an eye on merchant authorizations that exceed the limit—those will be declined.

    Use one‑time cards for clarity: they simplify bookkeeping, prevent overdraft surprises, and reduce fraud impact without complicating your recurring billing.

    Recurring Payment Challenges

    One‑time virtual cards give you tight control over single purchases, but they can cause headaches if a merchant needs to bill repeatedly. You’ll often find one‑use cards decline automatic charges for recurring subscriptions, forcing you to update card details or switch to a permanent card. That defeats the privacy and currency‑control benefits you wanted.

    To manage this, check whether your card provider supports tokenization or reissuable virtual card numbers tied to payment automation; these let merchants bill without exposing new credentials. Also confirm renewal rules, currency conversion limits, and merchant acceptance before subscribing.

    If seamless recurring billing matters, consider keeping a dedicated virtual card with controlled limits for subscriptions, and monitor statements to cancel unwanted charges quickly.

    Virtual Card Problems: Declines, Refunds & Disputes (What to Do)

    If a virtual card transaction is declined or you need a refund or dispute, act quickly to preserve your options and evidence. Check decline reasons first: card activation, transaction limits, merchant issues, or security concerns often explain failures. Gather receipts, timestamps, and screenshots to support your case.

    1. Contact the merchant with clear proof and request a refund; follow their refund process and note responses.
    2. If the merchant won’t cooperate, escalate to your card issuer for dispute resolution—provide collected evidence and reference user experiences if available.
    3. Monitor pending holds and final statements; keep records until the issue is resolved.

    Stay calm, document everything, and follow timelines the issuer or local regulations set to maximize your chance of success.

    How to Pick the Best Virtual Card: Security, Fees, Convenience

    How do you choose the right virtual card when priorities like security, fees and convenience pull in different directions?

    First, prioritize security features: look for tokenization, one-time numbers, and instant freeze/unfreeze controls so you can stop misuse immediately. Check issuer reputation and whether transactions are monitored for fraud.

    Next, compare fees: monthly, per-card creation, and foreign-exchange or withdrawal charges — the cheapest card can cost more if FX rules are poor.

    Then evaluate user experience: how fast you issue cards, mobile app clarity, and customer support responsiveness matter for real-world use.

    Finally, balance limits and flexibility — temporary limits protect you, while adjustable limits and easy top-ups preserve convenience.

    Test a low-stakes purchase before committing long-term.

    Frequently Asked Questions

    Can Virtual Cards Be Used for Recurring Billing Across Different Merchants?

    Yes — you can use virtual cards for recurring payments; you’ll enjoy merchant flexibility and subscription services support when the provider allows billing automation, but confirm card expiry, reuse policies, and merchant acceptance beforehand to avoid declines.

    Can Virtual Cards Be Linked to Apple Pay or Google Pay?

    Yes, you can link many virtual cards to Apple Pay or Google Pay; they’ll inherit security features like tokenization and biometric auth, and you’ll still be bound by issuer-imposed transaction limits and card-specific rules for payments.

    Do Virtual Card Transactions Affect My Credit Score or Credit Limit?

    Could virtual card use affect your score? Yes — it can influence credit utilization and appears in your transaction history; you’ll want to manage balances and payment timing, or it may lower your score or reduce available credit limit.

    Can I Transfer a Virtual Card Balance Back to My Turkish Bank Account?

    Usually you can’t transfer a virtual card balance back; virtual card limitations mean refunds follow the merchant’s refund process, returning funds to the original funding source or bank account, so you’ll request a refund rather than direct transfer.

    Are Virtual Cards Accepted for In-Person Chip-And-Pin or Contactless Payments?

    By golly, no — you generally can’t use virtual cards for in-person chip-and-pin or contactless payments. They prioritize security features and often have strict transaction limits, so you’ll use them mainly for online purchases.

    Final words

    You’ve learned how virtual cards can simplify spending, safeguard savings, and solve silly settlement snafus when shopping across borders. Choose a card with sensible security, straightforward fees, and speedy setup to stop scams, seize savings, and smooth subscription services. Test temporary tokens for tricky transactions, tweak limits to tame theft risk, and track transactions to troubleshoot declines. With careful comparison and cautious use, virtual cards give convenient, cost-conscious control over cross‑border online purchases.